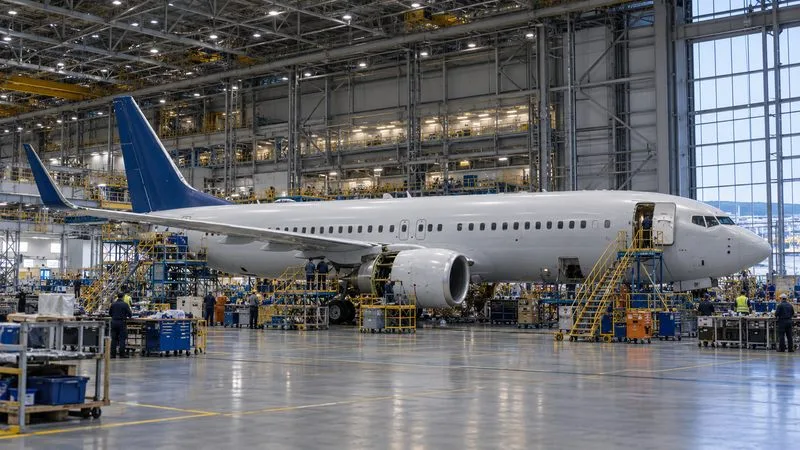
A passenger jet sits in a large assembly hangar. Boeing’s share-price recovery depends on turning production plans into stable, completed deliveries and stronger cash generation.
As of October 7, 2026, Boeing (NYSE: BA) looks like a high-risk recovery stock rather than a confirmed turnaround. The shares had fallen about 10% over the prior month and roughly 19% over three months in the October 6 market snapshot. Boeing’s second-quarter results showed improving revenue and positive free cash flow, but management said the 737 production system was still not stable at its targeted rate. For investors, the decision turns on time horizon and tolerance for execution risk: those who can absorb volatility may track the recovery in stages, while investors needing predictable earnings or low drawdowns may prefer to wait for evidence from the next quarter.
This is a dated trend review, not a real-time quote or a price target. Boeing is scheduled to report third-quarter results on October 27, so October’s full-month trend and the new operating data are not yet known.
What does Boeing’s October 2026 stock trend say?
Market data available on October 6 showed BA down 10.02% over one month, 18.57% over three months, and 12.03% year to date. The snapshot is a useful description of recent momentum, not proof that the shares must keep falling. The exact return can differ with the quote cutoff, dividends, and the measurement date; investors should confirm it against a consistent historical-price series before comparing Boeing with the S&P 500 or other aerospace stocks.
The near-term trend is weak, but it is not enough by itself to answer whether BA is attractive. Price weakness can reflect changing expectations for deliveries, margins, regulatory milestones, or broader market risk. A short-term chart also cannot show whether a production improvement is repeatable. Anyone using technical analysis should choose one time frame in advance, check the same data source for both BA and a benchmark, and avoid treating a temporary bounce as confirmation of a business recovery.
Why are investors still watching Boeing’s operations?
Revenue and cash flow improved in Q2, while profitability remained fragile
Boeing reported second-quarter 2026 revenue of $24.6 billion, up 8% from a year earlier, and delivered 171 commercial airplanes. It recorded a GAAP loss per share of $0.67 and a non-GAAP core loss per share of $0.76. Operating cash flow was $1.4 billion and free cash flow was $0.6 billion. The company’s backlog reached a record $715 billion, including more than 6,200 commercial aircraft.
Those numbers point in two directions. Higher deliveries helped revenue and cash flow, which supports the recovery case. Yet Boeing was still loss-making in the quarter, and backlog is a contracted pipeline rather than cash already collected. Investors should look for several quarters of completed deliveries, stable margins, and cash conversion before assuming that a large backlog will translate into durable earnings.
Production stability is the central near-term test
At the September 16 Morgan Stanley conference, CEO Kelly Ortberg said Boeing was driving toward 47 737 aircraft per month but was not yet stable at that rate; stabilizing the line was taking longer than he had expected. Boeing also said the 787 program had stabilized at a rate of eight aircraft per month and was working toward a possible increase to ten later in 2026. Those are operating targets and management statements, not proof that the rates have already been sustained.
This distinction matters for BA’s price trend. More factory starts do not necessarily mean more customer deliveries in the same period. Parts availability, rework, quality checks, certification, and airline acceptance all affect when an aircraft is handed over and when related cash is received. A useful follow-up is to compare quarterly deliveries with production-rate commentary and free cash flow, rather than rely on a single headline about factory output.
Certification progress helps, but timing still matters
The FAA granted the 737-7 an amended type certificate on August 3, 2026. At the September 16 update, Boeing described the 737-10 as being in the final documentation phase after flight testing, with certification expected soon. Boeing’s Q2 release continued to anticipate certification in 2026 and first deliveries in 2027 for both the 737-7 and 737-10. Certification can broaden the delivery opportunity, but the economic benefit depends on approval, production readiness, and actual customer handovers.
What would strengthen or weaken the recovery case?
| Evidence to monitor | Would strengthen the case | Would weaken the case |
|---|---|---|
| Commercial deliveries | Several quarters of rising, on-time handovers | Repeated delivery delays or inventory accumulation |
| Production rates | Management confirms stable output and quality | Target rates slip or quality issues interrupt flow |
| Cash generation | Free cash flow improves alongside deliveries | Cash flow depends on temporary working-capital benefits |
| Program costs | Commercial margins improve and fixed-price losses narrow | New charges offset volume gains |
| Certification | FAA milestones and first deliveries arrive on schedule | Certification or entry into service moves out again |
Q2 also showed why investors should inspect the segments separately. Commercial Airplanes reported $11.8 billion of revenue but an operating margin of negative 2.7%. Defense, Space & Security reported $7.5 billion of revenue and an operating loss of $15 million, including $280 million of losses on the VC-25B program. Global Services produced $5.3 billion of revenue and an 18.1% operating margin. A stronger Services result is helpful, but it does not eliminate execution risk in commercial production or fixed-price defense contracts.
Who might consider BA now, and who may want to wait?
A staged approach may suit investors who already understand that Boeing’s recovery could take years, can tolerate sharp price moves, and are prepared to review each earnings release. For example, rather than investing a full intended position after one down month, an investor could define a small initial allocation and add only after preselected operating evidence improves, such as stable 737 production and better free cash flow. The schedule and thresholds should reflect the investor’s own risk limits; staged buying does not guarantee a better price or prevent losses.
Waiting may suit investors who want lower uncertainty or need capital within a short period. The trade-off is that a confirmed improvement can be recognized by the market before the share price offers a lower entry. Waiting for two or more quarters of consistent deliveries, cash generation, and progress on certifications sacrifices some potential early upside in exchange for clearer operating evidence.
BA may be a poor fit for investors who need dependable near-term profits, have little room for volatility, or are buying solely because the share price has declined. A falling price is not a valuation argument by itself. Before committing, compare the company’s cash needs, debt and share dilution disclosures in current filings, and the size of the position with the rest of the portfolio.
What should investors check next?
Boeing announced that it plans to publish Q3 2026 results on October 27. Read the report for commercial deliveries, segment margins, operating and free cash flow, backlog conversion, and any updated timing for the 737-10, 777X, and production plans. Compare those figures with Q2 rather than with a management target alone. If deliveries rise but cash flow weakens or program charges grow, the recovery may be less durable than a simple price chart suggests.
For a clean October stock-price review, use daily closing prices through the final trading day of the month, calculate the month-to-date return from the September 30 close, and compare it with the same-period S&P 500 return. Then connect the chart to dated company disclosures. This separates market performance from operational evidence and prevents an incomplete week from being described as a full-month trend.
Sources and limits
- Boeing’s second-quarter 2026 results, released July 28, 2026.
- Boeing’s September 16 management update on production and certification.
- Boeing’s announcement of FAA certification for the 737-7.
- Boeing’s scheduled Q3 2026 results release.
- BA market-data page used for the October 6 performance snapshot.
All operating figures above are company-reported results or dated management updates. Stock performance is a market-data snapshot and changes with the selected cutoff. October 2026 was still in progress on October 7; this article therefore does not claim a full-month return or forecast a future price. This is general information, not individualized investment advice.