Why Natural Gas Jumped as Gold and Silver Fell on November 20, 2026
Natural gas rose 16% while silver and gold futures fell on November 20, 2026. See the verified market data, possible drivers, key caveats and next-session scenarios.
Checked November 20, 2026, at 4:18 p.m. EST (UTC−05:00). Chase offers several practical controls for credit card customers, including transaction alerts, card locking, two-step verification, and ways to report fraud through its app or by phone. These tools can reduce the time between suspicious activity and your response, but no alert or lock replaces reviewing transactions and contacting Chase through a trusted channel. This guide focuses on everyday card protection; it does not claim that a particular breach or attack affecting Chase customers has been confirmed.
Start with the login. Use a long, unique password that you do not reuse on email, shopping, or social media accounts. A password manager can create and store a different password for each service. If someone guesses or obtains a password from another website, reuse is what can turn that separate incident into access to your financial account.
Enable two-step verification in Chase’s Security & Privacy settings. Chase says it may use an app notification or a one-time code when a sign-in or account activity looks unusual. Its security guidance also describes an option to request verification at each browser sign-in. Protect the email account and phone number that receive those codes: set a screen lock, keep operating-system and app updates current, and contact your mobile carrier if you suspect someone transferred your number without permission. Chase supports biometric sign-in in its mobile app, but biometrics work best alongside a strong device passcode.
Use the official Chase app or type Chase’s known web address yourself. Do not follow a login link in an unexpected email or text. Chase advises customers to check that the address is truly on chase.com and to be wary of misspellings or extra words in look-alike domains. If a message says your account will be closed unless you act immediately, stop and verify through the app or the phone number on your card.
Set up account alerts that fit your spending habits, such as notices for purchases or activity requiring your attention. Chase says it monitors credit card purchases for unusual activity and may contact customers by text, email, or phone. Treat an alert as a prompt to check, not as proof that the message itself is legitimate. Do not share a one-time code or password with anyone who contacts you. If you are unsure, open the app independently or call the number on the back of your card.
If your card is misplaced, use Chase’s online account or app to lock it while you look for it. Chase says a lock blocks new purchases but does not stop recurring transactions. That means a lock is a short-term control, not a full account closure or a guarantee that every payment attempt will be blocked. If you believe the card number was stolen or you see a charge you did not authorize, contact Chase promptly and ask whether the account should be replaced.
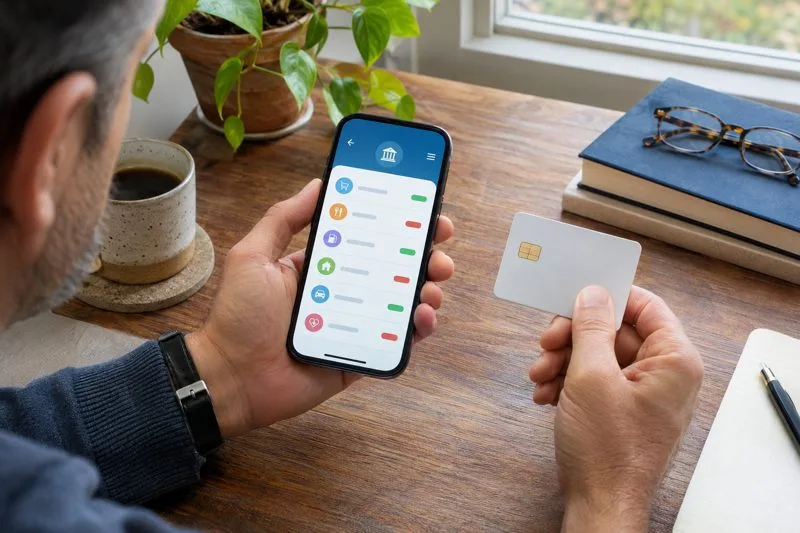
When connecting a budgeting or payment app, use the secure authorization flow offered by Chase instead of typing your Chase password into another service. Chase says connected apps can link directly without requiring you to give them your Chase username and password, and that you can manage or unlink access in the Security & Privacy Center. Remove connections you no longer use.
First, check the transaction details. A billing name may differ from a store’s familiar name, and a pending charge may not yet show full information. Chase distinguishes unauthorized transactions from charge errors, such as a duplicate purchase, a canceled subscription that billed again, or a charge for goods that never arrived. If you recognize the merchant but dispute the amount or service, that may call for a billing dispute rather than a fraud claim.
For a billing error, the Consumer Financial Protection Bureau says to contact the card company promptly and send a written billing-error notice to the address for billing inquiries within 60 calendar days after the charge appeared on your statement. Keep copies of the notice and supporting documents. This timing relates to the federal billing-error process; follow Chase’s instructions and your card agreement for the specific case.
Federal law generally limits liability for unauthorized credit card use to $50, and if only the account number was stolen—not the physical card—federal rules generally provide no liability for the unauthorized use. Many card agreements, including issuer policies, may offer broader protection, but do not assume that reporting can wait. Contact Chase as soon as you notice a problem, and review the terms that apply to your account. Credit card rules also differ from debit card protections, so these points should not be applied to a bank debit card.
If you suspect identity theft beyond one card transaction—for example, unfamiliar accounts or credit applications—consider placing a fraud alert or security freeze with the credit bureaus and use IdentityTheft.gov for a recovery plan. A credit alert does not replace reporting the Chase charge itself.
Yes. You can lock or unlock the card in your Chase account or app. Chase notes that recurring transactions may still be processed while the card is locked.
Chase lists 1-800-955-9060 for credit card fraud. You can also call the number printed on the back of your card or on your statement.
No. Open the Chase app yourself or call a trusted number from your card or statement. Never give an unsolicited caller a password or one-time verification code.
Sources: Chase Security Center; Chase guidance on protecting yourself; Chase: unauthorized charges and fraud steps; CFPB: disputing a credit card charge; FTC: credit cards and billing disputes.
Natural gas rose 16% while silver and gold futures fell on November 20, 2026. See the verified market data, possible drivers, key caveats and next-session scenarios.
Broadcom, Tesla and Meta fell sharply on November 20 as an AI-linked sell-off deepened. Here are the verified market drivers and conditional scenarios for Monday’s session.
Nvidia fell 14.0% to $125.53 on November 20 as a broad AI-stock selloff deepened and a Reuters report on SEC accounting scrutiny added pressure. Here are the verified factors and next-session scenarios.
U.S. stocks fell sharply on November 20 as AI-linked shares sold off. See reported index closes, why volatility surged, and what could shape the next session.
Coal River Farm is trading in the immediate term during voluntary administration. Here’s what customers should check about orders, bookings, and gift cards.
Bitcoin fell below $60,000 on Nov. 20 as a technology-stock selloff and ETF outflows weighed on risk appetite. See the latest verified BTC market context.
Coal River Farm is trading in the short term under administrator Adam Johnston, who is seeking urgent proposals for the Tasmanian cheese and chocolate business.
Australia’s TGA registered oral Wegovy and Foundayo in November. See what approval means for access, likely costs, safety and practical next steps.
Learn how GLP-1 medicines affect appetite, what the latest Australian approvals mean, and the safety questions to discuss with your clinician.
Australia’s TGA has registered Foundayo (orforglipron), a daily GLP-1 tablet for eligible adults. See what is approved, what remains unclear and how it compares with current options.