Colts vs. Cowboys: Live Score and How to Follow — November 8, 2026
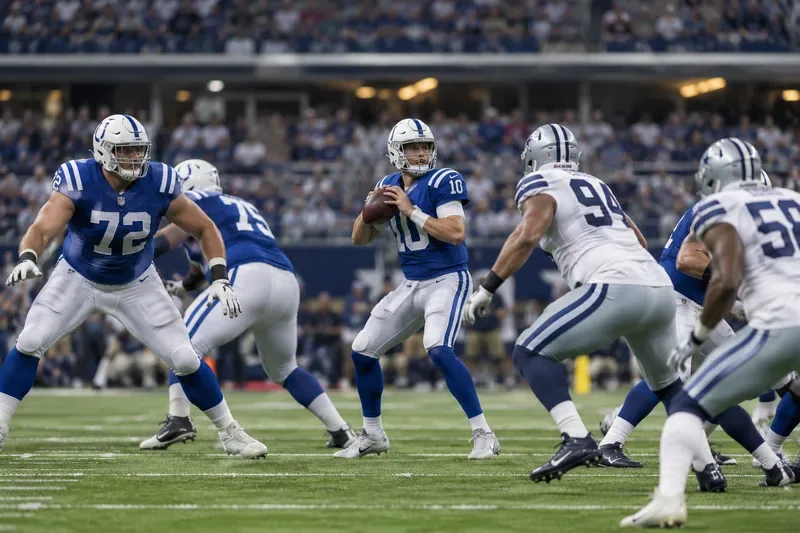
Track Colts vs. Cowboys on Nov. 8, 2026: official NFL live score, game time, Australian viewing options, updates and how to check the final result.
Information checked: November 8, 2026, at 5:05 p.m. UTC.
Retirement planners have a new reason to test their budgets: Social Security’s 2026 trustees report projects that the reserve for retirement and survivor benefits will be depleted in the fourth quarter of 2032. If the law remains unchanged and the trustees’ assumptions hold, continuing income would cover about 78% of scheduled benefits at that point.
That is a projection, not an enacted 22% benefit cut. Congress could change the program, and future economic and demographic conditions could shift the date or the size of the shortfall. Still, households that depend heavily on Social Security can use the estimate to prepare a backup plan now.
Destaques
A useful first step is to translate the projection into dollars. Suppose a household expects a combined $2,500 a month in gross retirement and survivor benefits. A simple 22% reduction would be $550 a month, leaving $1,950, or $6,600 less over a year. This is an illustration using the trustees’ 78% figure, not a prediction of any household’s actual payment or a description of legislation already passed.
Use gross benefits for this initial calculation, then build a separate estimate of take-home income. Taxes, Medicare premiums and other deductions can make the change in the amount deposited in a bank account different from the gross reduction. Future cost-of-living adjustments and any legislative changes would also affect the result.
Compare the possible gap with essential expenses such as housing, food, insurance and health care. A household with a pension, savings or flexible work income may be able to absorb a reduction differently from one relying on Social Security for most necessities. Include a surviving spouse’s potential income in the exercise, since household benefits and expenses can change after a death.
The Social Security Administration’s release on the 2026 trustees report identifies the fourth quarter of 2032 as the projected depletion point for the Old-Age and Survivors Insurance, or OASI, reserve. Its projected income at that time would cover 78% of scheduled OASI benefits.
The trustees also present an estimate for the retirement and disability trust funds considered together: reserves would be depleted in 2034, with income covering 83% of scheduled combined benefits at that point. The funds are legally separate; combining them for this estimate does not itself permit money to be transferred between them. The 2032 OASI projection is therefore especially relevant when stress-testing retirement and survivor income.
Reserve depletion would not mean that Social Security has no income. Payroll taxes and other dedicated revenue are expected to continue flowing in. The funding problem is that projected costs exceed that income, and reserves are being used to cover the difference. The trustees’ 2026 report summary explains the assumptions and notes that the OASI depletion estimate moved one quarter earlier than in the previous report.
Start with your own numbers rather than a national average. Review your earnings record and benefit estimates through your my Social Security account. Estimates depend on your earnings and claiming age and can change, so revisit them periodically.
Then make two retirement income projections: one using your scheduled estimate and another using 78% of the relevant gross retirement or survivor benefit as a stress test. Apply the lower scenario from the projected depletion period onward, not automatically to years before it. Keep other income sources separate so you can see the potential monthly and annual gap clearly.
Next, consider which adjustments are realistic for your circumstances:
A lower-benefit scenario is a planning tool, not a reason to make an abrupt investment decision. Consider whether your savings and investments suit your time horizon, need for accessible cash and tolerance for market losses. A qualified financial or tax professional can help assess trade-offs for your household.
Not necessarily. Claiming early generally reduces the monthly retirement benefit relative to claiming at full retirement age, while delaying beyond full retirement age can increase it up to age 70. The Social Security Administration’s claiming-age calculator explains how the adjustment depends on birth year and claiming month.
Compare claiming ages using both the scheduled-benefit and lower-benefit scenarios. Consider your health, other income, cash reserves and the possible effect on a spouse or survivor. An earlier claim can provide income sooner, but it also locks in an early-claiming reduction under current rules. The possibility of a future shortfall alone does not establish which choice is best.
No. The trustees project that the retirement and survivor trust fund’s reserves will be depleted then, not that dedicated revenue will disappear. Under their assumptions and current law, ongoing income would cover about 78% of scheduled OASI benefits at that point.
No. The figure is the difference between scheduled benefits and the trustees’ projected 78% payable from continuing income at OASI reserve depletion. Future legislation and economic conditions could change the outcome.
No. The 2032 estimate concerns the separate retirement and survivor trust fund. The trustees project that the separate Disability Insurance fund will have sufficient reserves throughout the 75-year projection period ending in 2100.
Track Colts vs. Cowboys on Nov. 8, 2026: official NFL live score, game time, Australian viewing options, updates and how to check the final result.
Buying Bitcoin in Australia? Understand price volatility, scams, exchange security, AUSTRAC checks, tax obligations, and 2026 regulatory changes.
Follow Bulls vs. 76ers on the NBA game tracker, check box scores and play-by-play, and find Australian start times and viewing options for Nov. 9.
Struggling with debt in Australia? Learn which bills to prioritize, how to request hardship assistance, and where to find free financial counseling.
England wants to protect Years 7–9 from early GCSE teaching and broaden lessons. Find out what could change, what stays, and when reforms begin.
Why was Spencer Leniu sin-binned against Australia? Learn how rugby league’s 10-minute suspension works and what could happen next.
Check the 2026 Brazilian Grand Prix results, Oscar Piastri’s finish, official FIA documents and where to follow Formula 1 updates.
Falkirk’s 5–2 win at Hearts moves them into third place on 21 points. See the updated Scottish Premiership standings and what happens next.
Learn how Bitcoin transactions, blockchain, mining, wallets, and supply work, along with the practical risks for users.
Bethany Antonia and Nancy Xu have left Strictly Come Dancing. Here’s what happened in the dance-off and when the show returns.