Home
» Equity Research
»
The TJX Companies (TJX) Stock Price Trend Analysis: What Matters in October 2026
The TJX Companies (TJX) Stock Price Trend Analysis: What Matters in October 2026
The TJX Companies, Inc. (NYSE: TJX) enters October 2026 with a mixed but useful setup for investors: the business is still producing positive comparable-sales growth and stronger-than-planned profitability, while the share price has been choppy enough that entry price matters. For a practical October review, the most important task is to separate what the company has already reported from what investors are still waiting to learn.
As of the October 5, 2026 regular-session close, TJX traded at $134.41. The company's own historical stock quote tool shows the preceding week clearly: $130.25 on September 28, $133.80 on September 29, $132.31 on September 30, $133.59 on October 1, and $132.68 on October 2. That sequence shows short-term recovery momentum, but not a straight-line uptrend.
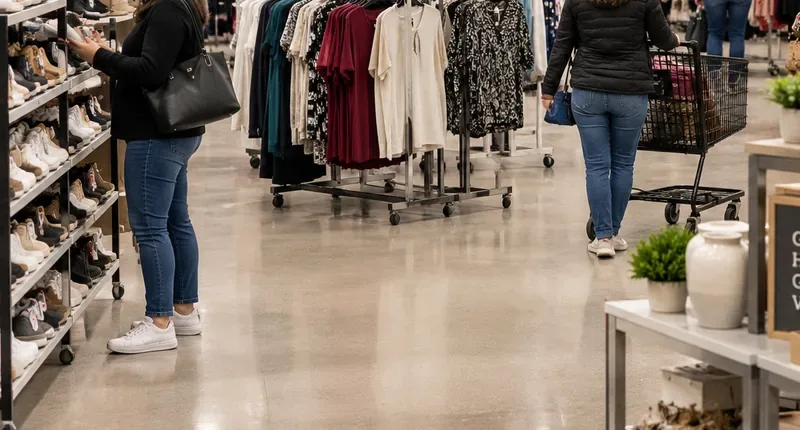
Shoppers move through clothing, footwear and home-merchandise aisles in a busy off-price retail setting, illustrating the store-based model that remains central to TJX's sales growth.
October 2026 TJX snapshot
Item
Latest verified reading
Why it matters
October 5 share price
$134.41 regular-session close
Useful reference point for evaluating whether earnings growth is already reflected in the price.
Q2 FY27 net sales
$15.2 billion, up 5% year over year
Shows continued top-line growth.
Q2 FY27 comparable sales
Up 4%
Indicates existing stores and digital operations continued to grow.
Q2 adjusted EPS
$1.22, up 11%
Removes the unusual tariff-refund benefit and gives a cleaner earnings comparison.
FY27 adjusted EPS guidance
$5.15 to $5.20
Provides the clearest current management benchmark for full-year profitability.
Long-term store target
7,500 stores
Signals that physical expansion remains a meaningful growth lever.
How should investors read the October price trend?
The most practical interpretation is that TJX is showing a short-term rebound after a volatile stretch rather than a confirmed long-duration breakout. From September 28 at $130.25 to October 5 at $134.41, the stock gained about 3.2%. Within that window, however, daily closes moved both higher and lower. That matters because a rising weekly endpoint can hide meaningful intraday or day-to-day volatility.
Action: If you are considering a new position, compare the current price with several recent closing prices rather than judging the trend from one session. A simple five- or ten-session range is more informative than one green day.
Business momentum is stronger than the stock chart alone suggests
TJX reported second-quarter Fiscal 2027 net sales of $15.2 billion, up 5% from a year earlier, while consolidated comparable sales increased 4%. For the first half of Fiscal 2027, net sales reached $29.5 billion, up 7%, and consolidated comparable sales rose 5%. Those are verified operating results, not analyst estimates.
The earnings picture also improved. Reported Q2 diluted EPS was $1.36, up 24% year over year, but that figure included a net benefit from tariff refunds. Excluding that benefit, adjusted diluted EPS was $1.22, up 11%. The distinction is important because investors who use the headline 24% EPS growth rate without adjusting for the unusual item could overstate the underlying operating acceleration.
Action: Use adjusted EPS and adjusted pretax margin when comparing TJX's underlying performance across periods, but keep the reported figures available as a reconciliation check.
Management raised guidance, but the next quarter still matters
After Q2, TJX maintained its expectation for full-year Fiscal 2027 comparable sales growth of 3% to 4%. It raised full-year adjusted pretax margin guidance to 12.0% to 12.1% and adjusted diluted EPS guidance to $5.15 to $5.20. For Q3, management planned for comparable sales growth of 2% to 3% and adjusted diluted EPS of $1.30 to $1.32.
This creates a practical test for the next earnings report: does the company at least meet its own Q3 comp-sales and adjusted-EPS ranges, and does it preserve the higher full-year outlook?
Action: Before buying solely because guidance was raised in August, write down the Q3 ranges now. When the next report arrives, compare actual results directly with those ranges rather than with market headlines.
Store expansion is an opportunity, not an automatic guarantee of higher returns
TJX ended Q2 with 5,285 stores, up 23 stores during the quarter. Management also said it plans to accelerate annual store growth to 4% beginning in Fiscal 2028 and increased its long-term global store target to 7,500 locations.
That expansion plan is meaningful because TJX remains overwhelmingly store-led. The latest 10-Q says combined e-commerce sales represented about 2% of total sales in both Q2 FY27 and Q2 FY26. In other words, the investment case is still tied heavily to merchandising, store traffic, inventory sourcing, real estate execution, and unit economics.
Action: Track store count together with comparable sales. More stores plus healthy comps is stronger evidence than store growth alone.
Do not confuse tariff-related benefits with permanent margin improvement
One of the easiest mistakes to make with the Q2 report is to treat all of the reported margin expansion as recurring. TJX reported a Q2 pretax margin of 13.3%, but adjusted pretax margin was 11.9% after excluding the net effect of tariff refunds and related compensation accruals. The company also disclosed in its 10-Q that the amount of any additional refunds remained subject to legal, regulatory, and administrative developments.
This does not make the reported result invalid. It simply means the cleanest trend analysis requires separating ordinary operating performance from unusual benefits.
Action: For valuation work, use the company's adjusted margin and adjusted EPS guidance as the base case, then treat additional tariff-related benefits as a separate scenario rather than a guaranteed earnings stream.
What supports the bull case in October?
Consistent customer demand: Q2 comparable sales grew 4%, following a strong first half.
Improved profitability: adjusted Q2 pretax margin rose 0.5 percentage points year over year.
Physical expansion runway: management raised its long-term target to 7,500 stores.
Capital returns: TJX returned $1.3 billion to shareholders through repurchases and dividends in Q2. Its 10-Q also shows quarterly dividends of $0.48 per share for each of the first two quarters of FY27.
Action: A bullish investor should verify that comp sales, adjusted margins, and store economics stay healthy together. One strong metric is not enough.
What could weaken the case?
Several risks are visible even without making a bearish prediction. TJX competes for discretionary consumer spending, must continually source desirable branded merchandise, operates a large store network, and has international exposure. Its 10-Q also notes currency effects: foreign exchange reduced Q2 net sales growth by about one percentage point. Fuel, wage, freight, tariff, and inventory costs can also affect margins.
There is also a valuation risk that exists whenever a company executes well: investors may already be paying for a substantial portion of expected growth. A strong company can still produce disappointing stock returns if future results merely meet expectations while the valuation contracts.
Action: Separate the question "Is TJX operating well?" from "Is TJX attractively priced at my entry point?" They are related, but they are not the same question.
What is still unknown in early October 2026?
The most important unknown is the actual Q3 FY27 result. TJX had not yet reported that quarter as of this analysis. The company's investor-relations news feed currently lists Q2 FY27 as its latest earnings release. Therefore, any claim that Q3 sales, margins, or EPS have already accelerated would be premature.
Another unknown is whether the recent share-price recovery will continue. Short-term price direction depends on market conditions as well as company-specific results, and no historical price pattern can establish what the next few weeks will do.
Compare Q3 comparable-sales growth with management's 2% to 3% plan.
Compare Q3 adjusted EPS with the $1.30 to $1.32 range.
Check whether full-year adjusted EPS guidance remains at least $5.15 to $5.20.
Watch adjusted pretax margin, not just reported margin affected by unusual items.
Track store growth together with comparable sales and square footage.
Review currency, freight, fuel, wage, inventory and tariff commentary in the next filing.
Decide your entry price before a volatile session rather than after one.
Bottom line
TJX's October 2026 setup is fundamentally stronger than a simple glance at the recent stock chart may imply. Q2 FY27 delivered 4% comparable-sales growth, 11% adjusted EPS growth, improved adjusted margin, and higher full-year earnings guidance. At the same time, the share price has been volatile enough that investors should not assume operating strength guarantees immediate upside.
For investors prioritizing business quality, the key evidence is continued comp-sales growth, adjusted margin expansion, disciplined capital returns, and a credible store-growth runway. For investors prioritizing entry price, the better approach is to combine those fundamentals with recent trading levels and wait for a valuation that fits their return requirements. For anyone focused on near-term confirmation, the next earnings report is the decisive checkpoint.
This analysis is for informational purposes and does not constitute individualized investment advice.