BYD Ti 7 vs. Land Rover: Dutch Court Lifts Evidence Seizure — Nov. 12, 2026
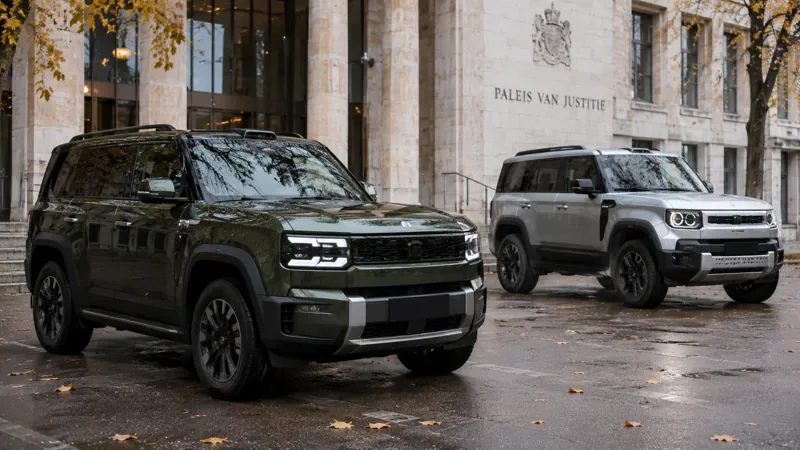
Why is Land Rover challenging the BYD Ti 7? A Dutch court lifted seized evidence on Nov. 11, but the Defender design dispute remains unresolved.
Verified and updated November 12, 2026, at 5:05 p.m. UTC.
The latest Social Security Trustees report projects that the Old-Age and Survivors Insurance (OASI) trust fund will deplete its reserves in the fourth quarter of 2032. That projection does not mean payroll tax collections stop: workers and employers would continue paying Social Security taxes, and the program’s ongoing income could still cover a substantial share of scheduled benefits. For workers, the practical issue is how contributions are divided today—and how future policy changes could affect take-home pay, employers, or benefits.
The 2026 report separately projects depletion in 2034 for the combined retirement, survivors, and disability (OASDI) trust funds, with ongoing income then sufficient to pay 83% of scheduled benefits under current law. The often searched 2032 date applies to the retirement and survivors fund alone. Both dates are projections based on assumptions and current law, not a guarantee of a specific future tax increase or benefit cut. Social Security Administration Trustees Report Summary
For most employees, Social Security is funded through Federal Insurance Contributions Act (FICA) payroll taxes. In 2026, the employee rate is 6.2% of covered wages, and the employer generally contributes another 6.2%, for a combined 12.4%. The Social Security portion is separate from Medicare payroll tax, which is generally 1.45% for the employee and 1.45% for the employer.
For example, an employee earning $60,000 in covered wages would generally have $3,720 withheld for Social Security over a full year, before considering any individual payroll circumstances. The employer would generally contribute another $3,720. The employee’s visible deduction is only their share; the employer match is an additional payroll cost. Self-employed workers generally pay both shares through self-employment tax, subject to applicable rules and deductions.
Social Security payroll tax applies only up to the annual taxable maximum. The 2026 cap is $184,500, so earnings above that amount are not subject to the 6.2% Social Security tax. Medicare tax has no comparable wage cap. See the IRS 2026 Employer’s Tax Guide for current rates and withholding details.
The OASI trust fund holds reserves that supplement incoming revenue when program costs exceed income. According to the 2026 Trustees summary, OASI reserves are projected to be depleted in Q4 2032. At that point, the report estimates ongoing income could cover 78% of scheduled OASI benefits. The combined OASDI projection is different: its reserves are projected to deplete in 2034, when ongoing income could cover 83% of scheduled benefits.
Reserve depletion is not the same as the program having no income. Payroll taxes would still be collected, and the system also receives income from taxes on some benefits and interest on reserves while reserves remain. The percentage estimates describe the gap between projected income and benefits scheduled under current law at the projected depletion point; they do not state what Congress will ultimately do. Lawmakers could change taxes, benefits, or other program rules, but the timing and contents of any legislation are uncertain.
For workers, the near-term paycheck effect is the tax rate and wage cap in force for that year, rather than an automatic change triggered by a forecast date. A future legislative change could affect employee withholding, employer payroll costs, benefit formulas, or some combination. Its effects would depend on the law enacted, who is covered, and when changes take effect.
Payroll contributions help finance benefits paid to current retirees, people with disabilities, and eligible family members. Social Security is not an individual savings account in which each worker’s tax is set aside under their name. A worker’s eventual benefit is generally calculated using their recorded earnings history and claiming circumstances, while current payroll revenue supports the overall program.
That makes accurate earnings records a concrete concern. Workers can review their Social Security earnings history through a my Social Security account and report errors to the agency. An omitted or incorrect year of covered earnings could affect the record used to estimate future benefits. Keep copies of W-2 forms and tax returns that can help substantiate a correction.
Workers can also use the SSA’s benefit tools to review estimates under their recorded earnings and different claiming ages. Treat the estimate as a planning input, not a promise that Congress will leave every program rule unchanged for decades. For household planning, it can be prudent to consider a range of retirement income scenarios, account for other savings and pensions, and revisit assumptions periodically.
The Trustees update their projections each year using assumptions about factors such as wages, employment, life expectancy, birth rates, inflation, and program costs. A different economic or demographic path can shift a projected date and the estimated share of benefits payable from ongoing revenue. Legislative changes can also alter program finances. The 2032 and 2034 dates should therefore be read as estimates under stated assumptions, not countdown clocks.
The 2026 report says OASI costs are projected to exceed income including interest starting in 2021, which means reserves are used to help meet costs. In the combined funds, the Trustees project total cost to exceed total income in 2026. The reserve drawdown explains why the reserve balance matters: payroll taxes remain central, but under the projection they alone and other continuing income would not fully cover scheduled benefits after reserves are depleted.
For an individual worker, no special action is required because a report gives a projected depletion year. The useful steps are ordinary financial housekeeping: verify the earnings record, understand the employee tax shown on pay statements, and avoid basing a long-term plan on a single forecast. For the official rates, wage cap, and annual projections, consult the IRS and SSA source pages linked above.
No. Payroll taxes are expected to continue. The projection is that ongoing program income would cover less than all scheduled benefits at reserve depletion unless the law or finances change.
No. The 2026 Trustees report projects OASI reserve depletion in Q4 2032 and combined OASDI reserve depletion in 2034.
Generally, 6.2% of covered wages up to the $184,500 wage base. The employer generally pays a matching 6.2%.
Why is Land Rover challenging the BYD Ti 7? A Dutch court lifted seized evidence on Nov. 11, but the Defender design dispute remains unresolved.
Ghana and Somalia are in Group C of AFCON 2027 qualifying. Here’s how the six-match group stage, points, tiebreakers, and qualification places work.
How do El Niño and the polar vortex affect UK winter weather? The Met Office explains November’s cold shift, snow risks and what remains uncertain.
The M5 near Taunton has overnight closures and a 50 mph, two-lane restriction. Check official updates and diversion details before setting off.
Understand UK winter weather warning colours, likely travel and home impacts, and practical steps to prepare for snow, ice, and severe cold.
Türkiye hosts Belgium on Nov. 12, 2026, at 8 p.m. in İzmir (noon EST). Check the UEFA Nations League kickoff and U.S. viewing options on FS1 and ViX.
Tim Cook is trending after a remark linking him to Nvidia’s leadership. Here’s what is confirmed about Apple and Nvidia’s AI and chip relationship.
Morgan Wallen’s Last Time I Checked Tour is confirmed for 2027. Find the official presale schedule, registration deadline, ticket links, and safe ways to check dates.
See how payroll taxes fund Social Security, what the 2026 Trustees forecast for reserves means, and which practical steps workers can take now.
The 2026 Trustees Report projects the Social Security retirement and survivor fund could be depleted in late 2032. Here is what that means for benefits and what it does not mean.