Home
» Today
»
AI Bubble Explained: What It Means and Why People Are Talking About It
AI Bubble Explained: What It Means and Why People Are Talking About It
The “AI bubble” is the concern that investors, companies, and lenders may be pricing in bigger or faster returns from artificial intelligence than the technology can deliver. The phrase does not mean AI is useless or that every AI company is overvalued. A technology can create lasting value while particular investments, products, or stock prices still disappoint.
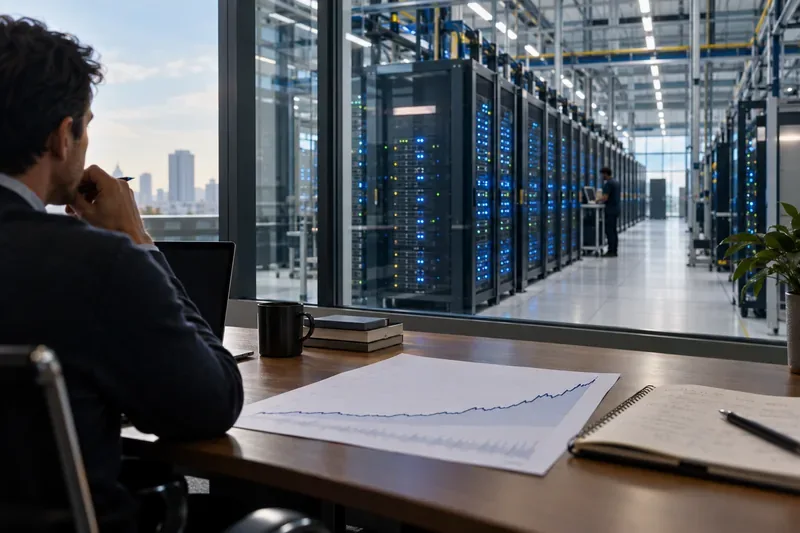
An analyst reviews a rising chart beside a glass-walled data center as AI investment expands.
As of October 27, 2026, the most useful way to assess the debate is to separate three questions: Is AI useful? Can providers earn durable profits from it? And do current valuations and financing plans already assume more than those profits can support?
Why are people talking about an AI bubble?
Investment has climbed quickly. Stanford HAI’s 2026 AI Index estimates that global private investment in AI reached $344.7 billion in 2025, a 127.5% increase from 2024. Generative AI companies drew $170.9 billion, nearly half of that total. These figures track private investment in AI companies; they are not the same as the stock-market value of AI firms or a complete measure of every company’s spending on chips, data centers, and power.
That spending builds an expensive chain of infrastructure: advanced chips, server farms, cloud capacity, electricity, and the models and services that run on them. Large budgets can make sense if customers keep paying and the infrastructure is used profitably. They become a concern when building capacity races ahead of durable demand, or when a company’s revenue cannot cover computing, staffing, depreciation, and financing costs.
The financing links are also drawing scrutiny. In its October 2026 analysis of the AI ecosystem, the International Monetary Fund describes connections among equity investment, borrowing, and commitments to buy future services. Such arrangements can tie companies’ fortunes together. The IMF says these links could amplify shocks if expected AI revenue or productivity gains fall short; it also says current stability risks appear manageable. Interconnected financing is a risk to examine, not proof that a bubble exists.
Actual use is growing, but it is not yet universal. The U.S. Census Bureau’s Business Trends and Outlook Survey found that overall business use stayed between 17% and 20% from December 2025 through May 3, 2026. The survey’s wording changed in November 2025 to ask about AI in “any business function,” so readers should be careful when comparing that period with older estimates. Use also differed by company size: 37% of firms with at least 250 employees reported using AI.
A separate Census household survey asked workers about 11 job tasks. In March 2026, 56% said they had used AI for at least one of those tasks. Among workers who had used AI at work in the last week, 31% said it saved them one to two hours. Those are self-reported survey results, not a controlled measurement of economy-wide productivity, but they show why the discussion is not only about stock prices: people are already trying the tools in routine work.
A real technology can still have a bubble around it
A bubble is usually a market condition in which prices depend heavily on optimistic expectations that may not be justified by future earnings or cash flows. There is no official test that can label the entire AI sector a bubble in real time. “AI” covers very different businesses, including chipmakers, cloud providers, model developers, software companies, and power and data-center operators. Their costs, customers, competitive advantages, and valuations are not interchangeable.
The dot-com boom is a useful comparison in one limited sense: a transformative technology can attract more investment than many firms can turn into lasting profits. It is not a template that predicts the timing or size of an AI correction. Some companies may build profitable businesses, while others fail, even if the underlying technology continues to improve.
The IMF’s October 2026 Global Financial Stability Report says weaker or less durable AI investment and profitability could lead to a correction in AI-related asset prices. It warns that rising leverage and concentrated exposures could make a correction more disruptive. That is a risk scenario, not a prediction that a crash is imminent.
How to evaluate an AI bubble claim
For a company, investment, or product, look for evidence beyond a rising share price or a widely used demo. These questions help separate adoption from expectations:
Are customers renewing and paying? Track repeat use, retention, and revenue from customers, rather than free trials, pilot programs, or announced partnerships alone.
Does the service make money after delivery costs? Compare revenue with the cost of computing, human review, support, security, and integration. A busy product can still have weak economics.
Is the promised benefit measurable? Ask whether a tool reduces the full cost or time of a task after checking errors and rework—not just whether it produces a fast answer in a demonstration.
Can the infrastructure earn back its cost? Look at capacity use, power availability, financing terms, and how quickly equipment may become outdated. A data center with customers and steady utilization is different from capacity built on speculative demand.
Who carries the risk if plans change? Examine debt, future purchase commitments, dependence on a small group of suppliers or buyers, and financial ties between companies. Interdependence can magnify the effect of a canceled deal or slower growth.
What expectations are built into the price? Consider more than one outcome. If a valuation works only if growth stays exceptional for years, even a successful product may not make the investment worthwhile at that price.
What would a correction mean?
If investors pull back, the effects could include lower valuations, fewer funding rounds, canceled data-center projects, and pressure on startups that depend on continued financing. Companies with weak sales or heavy costs may disappear. Businesses with useful products and stronger finances could continue operating, and lower-cost or more efficient approaches may gain ground.
A fall in AI-related share prices would not by itself prove that the technology has no value. Nor would widespread use guarantee that today’s investments will earn their expected returns. For workers and business owners, the practical question is whether a tool improves a specific workflow safely and reliably. For investors, the question is whether the price and financing terms leave room for slower adoption, stronger competition, and lower margins.
The short answer
An AI bubble is a possibility that expectations and investment have run ahead of the profits that AI can reliably produce. Rapid funding, costly infrastructure, uneven business adoption, and tightly connected financing help explain why the question is prominent. They do not settle it. Judge the evidence company by company: paying customers, repeat use, sound margins, productive infrastructure, and financing that can withstand a slower path to returns.