Home
» Today
»
ATO Deduction Warning Letters: What 26,500 Australian Taxpayers Should Know — November 12, 2026
ATO Deduction Warning Letters: What 26,500 Australian Taxpayers Should Know — November 12, 2026
Information checked: November 12, 2026, 5:09 p.m. AEDT (Sydney, UTC+11:00; 06:09 UTC).
The Australian Taxation Office is contacting taxpayers whose work-related deduction claims stand out against those of people in broadly comparable circumstances. Reporting on November 11 cited ATO-supplied figures indicating around 26,500 Australians had received follow-up letters. The development puts renewed attention on a simple distinction: an unusually high deduction is not necessarily a wrong deduction, and a review letter is not automatically a finding of wrongdoing.
The immediate consequence depends on the exact wording of the notice. Some recipients are asked to check their own claims; others may be asked for evidence or a response by a stated deadline. A legitimate expense can remain deductible even when it exceeds an occupational average, provided it meets the applicable tax rules and can be substantiated.
Destaques: Key takeaways
About 26,500 letters were reported on November 11, but this number comes from reporting based on information supplied by the ATO rather than a newly published ATO statistical bulletin.
The ATO compares deductions with patterns in similar returns and other available data; being flagged is not itself an assessment or penalty.
Read the individual notice carefully: a request to review your deductions is different from a formal request for supporting documents.
Keep proof of expenses, verify that any communication is genuine, and correct mistakes through the ATO’s official amendment process if necessary.
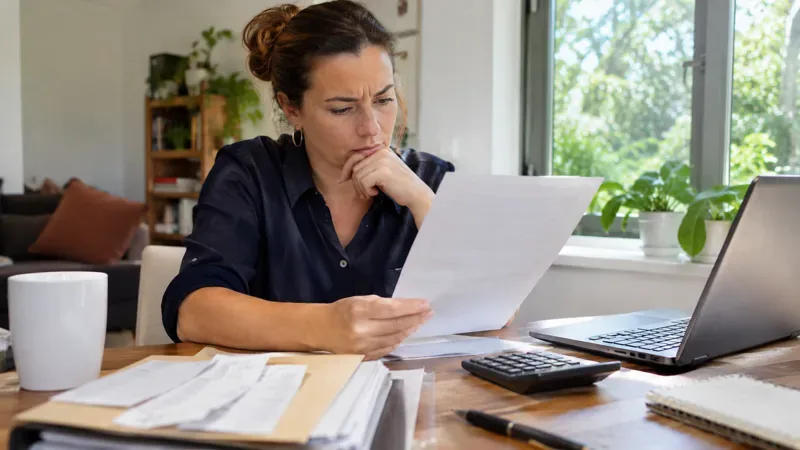
Illustration: A taxpayer reviews a letter alongside receipts and other financial records. This is a staged image, not an actual ATO notice.
Why is the ATO sending tax deduction warning letters?
The latest reporting describes a targeted compliance exercise linked to 2025–26 returns, rather than a blanket allegation against Australians who claim above-average deductions. The ATO uses data-matching and analytical checks to identify expenses that appear out of line with comparable taxpayers. Employers, financial institutions, government agencies and other third parties provide information that may help the agency detect discrepancies.
There is an important limit to what these comparisons reveal. Two employees with similar salaries and job titles can have very different legitimate costs. One may drive a personal vehicle between work sites; another may rarely leave an office. The ATO can ask questions about a claim without having established that it is false.
These warning letters follow the ATO’s broader 2026 focus on work-related expenses. According to ATO figures reported by ABC News in June, approximately 10.1 million people had claimed $31.1 billion in work-related deductions for 2024–25 at that point. Those figures describe an earlier tax year, not the monetary value of claims in the present letter campaign.
Which deductions are most likely to attract attention?
Working from home expenses
For 2025–26 returns, the ATO states that eligible taxpayers using the fixed-rate method can claim 70 Australian cents per hour worked from home. They still need records of their actual hours and must satisfy the relevant conditions. The actual-cost method is an alternative where the taxpayer can calculate and substantiate eligible costs. A claim calculated from a guessed weekly schedule, rather than adequate records, is vulnerable to challenge.
Car, travel, clothing and training expenses
Vehicle and travel claims must reflect qualifying work use, not ordinary private commuting. Clothing deductions are subject to specific rules: everyday clothes do not become deductible merely because they are worn to work. Education expenses must have the required connection to current income-producing activities. The existence of a receipt alone does not establish the tax treatment of an expense.
Mixed personal and work use
Phones, internet services and electronic devices often serve both purposes. Only the qualifying work-related share is generally claimable. The ATO’s guidance also emphasizes written evidence for relevant phone and data expenses. Taxpayers should be able to explain how any allocation was calculated, rather than assigning an arbitrary percentage.
What should you do if an ATO deduction warning letter arrives?
Verify the sender. Open myGov or ATO online services through a web address you type yourself; do not sign in through an unexpected text or email link. For a paper notice, independently obtain the ATO’s contact details.
Identify the type of correspondence. Note the tax year, the deductions singled out, whether the ATO is simply suggesting a review, and any specific response date.
Reconcile every flagged claim. Compare the amounts in the lodged return with receipts, invoices, diary entries, travel records, timesheets and reimbursement records, as appropriate.
Check eligibility, not just totals. Ask whether you incurred the cost yourself, whether your employer reimbursed it, whether it was connected to earning income and whether private use was excluded.
Act on actual errors. If the return is incorrect, use the official amendment process or consult a registered tax agent. If the claim is valid and the letter only asks you to self-review, keep your evidence; if it requests a response, meet the stated deadline or contact the ATO to discuss it.
Do not assume that a deadline reported in a news story applies to your notice. The relevant date is the one supplied to you by the ATO. Nor should taxpayers assume that every voluntary amendment automatically eliminates interest or penalties; the outcome depends on the circumstances and the ATO’s applicable rules.
Does a warning letter mean an audit, a fine or a lost tax refund?
No automatic conclusion follows from receiving a warning. A comparison letter can be a prompt to double-check information. A formal review may require records, and an audit may involve more extensive examination. If the ATO ultimately disallows deductions, the tax assessment can change and additional amounts may become payable. But neither the existence of a letter nor a comparison chart alone proves an incorrect claim.
Taxpayers with unusually high but legitimate work costs should not delete deductions simply to match an average. Conversely, keeping an unsupported claim because a refund has already arrived may create problems if the ATO later requests evidence.
Does the proposed $1,000 standard deduction change these letters?
No. The ATO’s 2026 tax-time materials say the proposed standard work-related deduction does not apply to the 2025–26 tax return. Official public guidance has described it as a proposal for the 2026–27 income year, subject to the relevant legislative position. It should not be used to justify claims in an earlier return or to disregard a current request for records.
What could happen next for Australian taxpayers?
Further targeted messages or information requests are possible as the ATO processes and reviews returns, but no additional campaign size or new deadline has been independently confirmed for this article. Taxpayers should rely on their own correspondence rather than predictions about mass audits. The practical lesson is to preserve contemporaneous records and ensure claims are defensible before and after lodgment.
Impersonation scams are an added concern. Scamwatch warned in June 2026 that criminals impersonate the ATO and myGov through calls, texts, emails and imitation websites. Unexpected demands to click a link, disclose credentials or pay immediately should be checked through official channels.
Frequently asked questions
Do I have to respond to every ATO deduction letter?
No. Check the wording. A general review reminder may not require a reply, but a formal request for information or a dated response must be addressed.
Can I claim more than other people in my occupation?
Yes. There is no universal cap based on an occupational average. Your expense must qualify under the law and you need the relevant proof.
How can I check whether an ATO letter is genuine?
Sign in directly through myGov or ATO online services and check available communications, or contact the ATO using details from its official website. Not every review or audit letter appears in online communication history.
Reporting note: The approximately 26,500-letter figure was attributed to ATO-provided information in a November 11, 2026, Nine report. An independently published ATO bulletin confirming that exact campaign total was not identified during this check. This article provides general information, not individualized tax advice.