Home
» Today
»
Trump’s Mortgage Executive Order: What Homeowners Should Check Before Refinancing
Trump’s Mortgage Executive Order: What Homeowners Should Check Before Refinancing
President Donald Trump signed the executive order “Decreasing Housing Costs for the American People” on October 22, 2026. Despite the mortgage-relief headlines, it does not set a new rate for every U.S. refinance or make a lender approve a loan. It directs federal housing agencies to pursue conditional programs that could lower some costs for eligible borrowers.
Illustrative example—not a real borrower or quote: Jordan has a conventional mortgage with private mortgage insurance (PMI) and sees a refinance offer after reading about the order. Jordan should check existing PMI cancellation rights and compare the written loan terms now, instead of assuming a new federal pilot has already reduced the price.
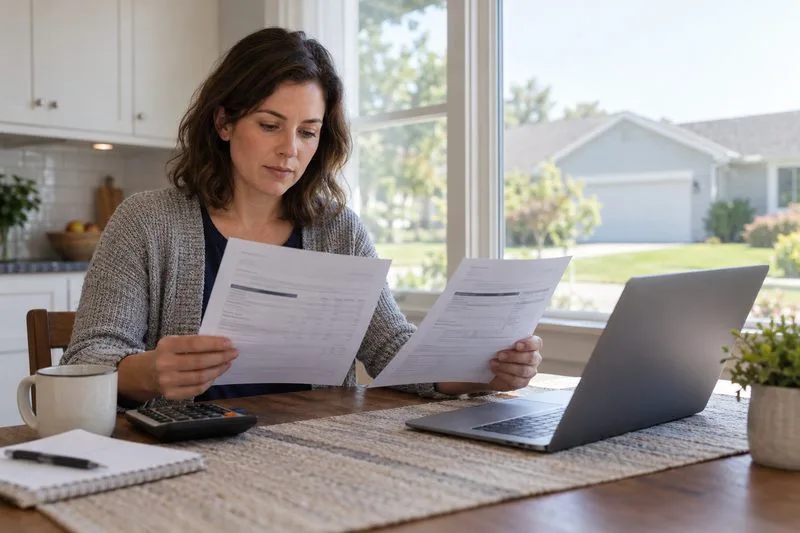
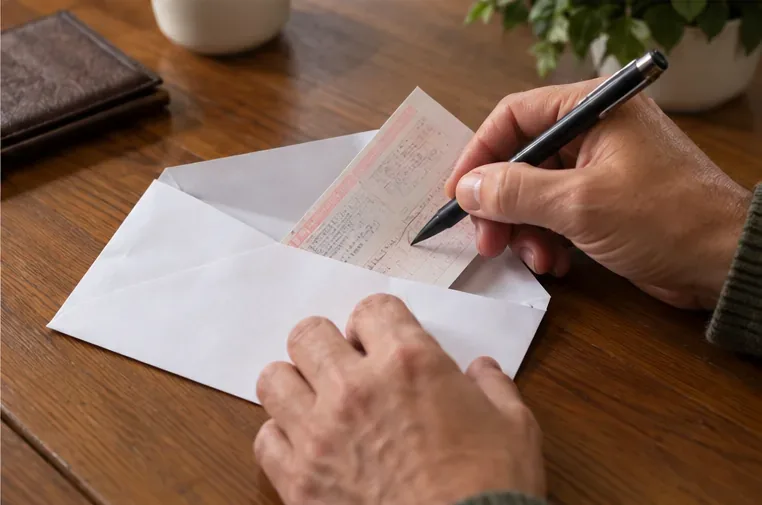
A homeowner compares mortgage paperwork before deciding whether refinancing costs are worth the potential savings.
What the mortgage executive order changes
The October order includes several housing measures, but three provisions matter most to homeowners weighing a refinance:
A possible future mortgage-insurance cancellation pilot
The order directs the Federal Housing Finance Agency (FHFA), if the director makes specified findings, to have Fannie Mae and Freddie Mac establish a pilot that reviews certain single-family loans for possible mortgage-insurance cancellation. The proposed review could use automated home-value estimates and other data to assess current value, along with payment history, equity, safety-and-soundness standards, and other legal or contractual requirements.
The order says this pilot would apply only to mortgages made after the program is established. It is not an automatic cancellation for existing borrowers, and it does not apply to every mortgage. The order does not give borrowers a launch date or an individual savings amount; check for FHFA, Fannie Mae, Freddie Mac, or servicer instructions before counting on the pilot.
Some conventional borrowers already have PMI cancellation rights under existing law. For covered mortgages, a borrower may generally ask the servicer to cancel PMI when the scheduled balance reaches 80% of the home’s original value, subject to requirements such as a good payment history and no junior liens. Automatic termination generally occurs at 78% if payments are current. FHA and VA mortgage-insurance rules differ. Jordan should ask the servicer whether current rules already allow PMI cancellation; refinancing may not be necessary just to make that request. The CFPB’s PMI guidance explains the conditions.
A planned expansion of title review for some refinances
The order directs FHFA, subject to the director’s findings and applicable law, to expand the existing title-acceptance pilot into an ongoing nationwide program through both Fannie Mae and Freddie Mac. In eligible refinances, an automated title review or another approved assessment could take the place of the lender’s title insurance policy. FHFA is also directed to consider expanding eligibility above the pilot’s current 80% loan-to-value limit when title risk is low, removing geographic limits, adding title-assessment providers, and reducing some documentation or fees for certain limited cash-out refinances that lower a borrower’s monthly payment.
That is a direction to expand a program, not a blanket waiver already available to every homeowner. Fannie Mae currently lists its existing Title Acceptance pilot as active for certain refinance transactions through November 30, 2027; the order calls for a broader ongoing program. Ask the lender whether the specific loan is eligible and whether any savings appear on the written Loan Estimate. The order says cost savings from the expanded program must be passed through to borrowers and disclosed.
Also ask what coverage you would receive. The pilot concerns lender’s title insurance, which protects the lender; it is separate from an owner’s title insurance policy a homeowner may choose to buy. FHFA’s pilot FAQs explain the distinction and the existing pilot’s limited scope.
Lower rates for a narrow set of direct government loans
The order tells the Secretaries of Agriculture and Veterans Affairs to reduce rates on single-family home loans made directly by their departments, consistent with law and available funding. Its wording does not promise lower rates on all conventional mortgages, all private-lender refinances, or every VA-guaranteed or USDA-backed loan. If you have one of these government-related loans, ask the agency or servicer whether your specific program is covered and when any revised rate takes effect.
The White House fact sheet also refers to earlier 2026 housing actions, including a separate direction for Fannie Mae and Freddie Mac to buy mortgage-backed securities. That January announcement is distinct from the October executive order discussed here.
What to check before refinancing
Identify your current loan and insurance. Ask your servicer whether the loan is conventional, FHA, VA, or USDA, and whether Fannie Mae or Freddie Mac owns or guarantees it. Confirm whether you pay borrower-paid PMI, FHA mortgage insurance, or another fee. Rules and possible order provisions depend on the loan type.
Request comparable written offers. Get Loan Estimates from multiple lenders for the same loan amount, term, and loan type. Compare the interest rate and rate-lock period, principal-and-interest payment, total monthly payment including mortgage insurance and escrow, lender fees, points, lender credits, cash to close, and the five-year cost. The CFPB Loan Estimate comparison guide identifies the fields to review.
Calculate a break-even point. Divide the refinance costs you will actually pay by the monthly savings you expect. In an illustrative calculation, if Jordan’s costs are $4,200 and the new principal-and-interest payment is $175 lower each month, the simple break-even point is 24 months ($4,200 ÷ $175). This is only a starting point: include any change in PMI, consider how long you expect to keep the loan, and compare the remaining term with the new term.
Check whether a lower payment costs more over time. A refinance can restart the repayment clock or add costs to the balance. Compare principal paid and total interest, not just the monthly payment. A “no-closing-cost” offer may use a higher rate or add fees to the new loan, which can increase long-term costs and reduce equity.
Ask what is effective today. Have the lender identify any title-review alternative, waived appraisal, reduced fee, or insurance change in writing. Do not count a proposed pilot benefit until the lender confirms that it is operating, your loan qualifies, and the savings are included in the estimate.
Before closing, compare the final Closing Disclosure with the latest Loan Estimate. Question any unexplained change in rate, loan amount, fees, mortgage insurance, or cash due. If Jordan’s current PMI can be canceled under existing rules, that may be a simpler option than replacing the mortgage—but the right choice depends on the actual written costs and loan terms.