Home
» Today
»
Why Are Stamp Duty Receipts Falling? What UK Homebuyers Should Know
Why Are Stamp Duty Receipts Falling? What UK Homebuyers Should Know
The claim that stamp duty receipts have fallen needs context. The widely shared £541 million figure is a Knight Frank estimate for sales of homes priced above £5 million in England; it is not a reported £541 million fall in all UK stamp duty. HMRC’s latest broad Stamp Taxes total was actually higher year over year, while the Office for National Statistics (ONS) separately said stamp duties were below forecast. Those figures measure different things.
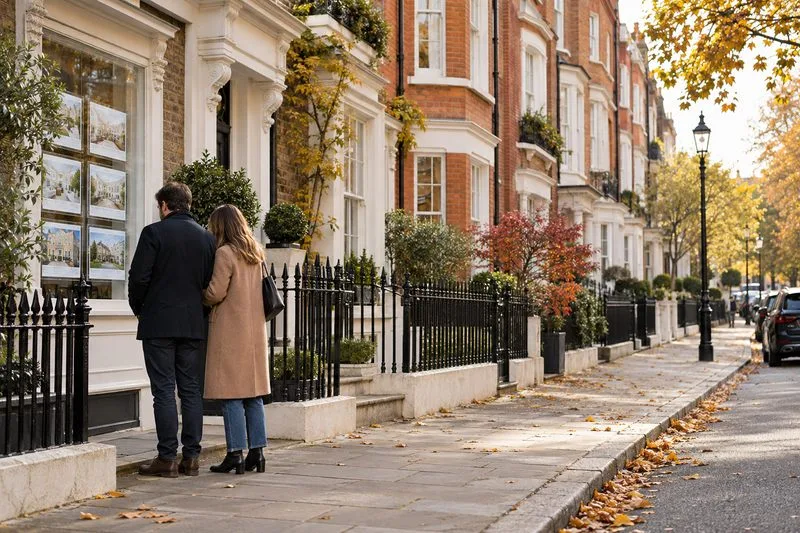
A couple looks at property listings on a London residential street.
What the recent receipts figures actually say
Measure
Latest figure
How to read it
High-value home sales
Estimated SDLT on England sales above £5 million fell 16%, from £3.395 billion to £2.855 billion, across two 18-month periods.
Knight Frank’s analysis; a narrow, modeled segment, not an HMRC total.
HMRC Stamp Taxes
£10.1 billion for April–September 2026, up £0.2 billion from the same months in 2025.
A broad cash-receipts category, not residential SDLT alone; excludes Scotland’s and Wales’s devolved property taxes.
Stamp duties versus forecast
ONS put receipts £1.5 billion below the OBR forecast for the financial year through September 2026.
A forecast gap, not proof that receipts fell year over year.
Knight Frank compared the 18 months before and after the October 30, 2024 Budget, adjusting the £5 million threshold for price movements. It counted 2,208 sales above that threshold in England after the Budget, down 14% from 2,569 before it. Its estimate also assumed that half of buyers paid both the additional-property and non-UK-resident surcharges, applying those assumptions evenly across the sales. The firm estimated that the higher additional-property surcharge raised £201 million, leaving a net £541 million decline in modeled receipts. This is an industry estimate, not a separately published HMRC tally or a controlled test proving the Budget caused the sales decline. Read the original Knight Frank analysis alongside the official figures.
HMRC’s latest transaction release adds useful context: seasonally adjusted UK residential completions in August 2026 were provisionally 95,220, 2% below August 2025 and 1% below July 2026. HMRC notes that these completions usually follow an offer by two to four months, so the data lag current buyer interest. Its monthly receipts bulletin also says activity was pulled forward before the April 2025 SDLT threshold changes, which makes some year-on-year comparisons unusually sensitive to timing.
Why high-end receipts can fall
Stamp Duty Land Tax (SDLT) is charged on portions of a purchase price, with higher rates on upper portions. A small number of very expensive sales can therefore contribute a large amount of tax. If those deals are delayed, priced below a cutoff, or do not happen, receipts can fall sharply even when ordinary home sales are steadier.
Policy changes may also alter when buyers complete or whether they buy. From October 31, 2024, the higher rate for additional dwellings rose from 3 to 5 percentage points above the standard residential SDLT rates. The UK also replaced the non-dom remittance-basis system with a four-year foreign income and gains regime from April 6, 2025. Knight Frank links the prime-market decline to the tougher policy environment, but timing alone cannot show how much each tax change contributed; financing costs and wider market conditions can also affect demand.
Threshold changes create another timing effect. Buyers sometimes complete before a tax-free band is reduced, shifting transactions into an earlier month. HMRC recorded higher activity before the April 2025 change and lower activity afterward. A monthly dip can therefore reflect a calendar shift as well as a lasting change in demand.
What it means for a homebuyer now
A fall in receipts does not automatically lower your bill or signal that a tax cut is coming. Your liability depends on where the property is, the completion date, price, whether you qualify for relief, whether you already own another home, and—in some cases—your residency status. For England and Northern Ireland, current standard SDLT rates apply progressively: 0% up to £125,000, 2% on the next £125,000, 5% from £250,001 to £925,000, 10% from £925,001 to £1.5 million, and 12% above £1.5 million.
For example, on a £350,000 purchase in England or Northern Ireland, a buyer paying standard rates owes £7,500, assuming no special relief or surcharge. An eligible first-time buyer purchasing for £350,000 owes £2,500: no SDLT on the first £300,000, then 5% on the remaining £50,000. First-time buyer relief is unavailable if the purchase price is above £500,000, and all joint buyers must qualify. Use HMRC’s current residential rate guidance and SDLT calculator for your own completion date and circumstances.
Compare the tax by buyer type and location
If you are…
Practical trade-off to check
A first-time buyer in England or Northern Ireland
Relief can reduce the upfront tax, but it has a £500,000 price cap. Check the exact purchase price before relying on it.
Replacing a main home
If the old home is still owned at completion, the additional-property rates may apply initially. A refund may be available if you sell the previous main home within 36 months.
Buying a second home or buy-to-let
The 5-percentage-point surcharge can materially increase upfront cost. Compare the full tax bill with your expected rental return or use of the property.
Buying in Scotland or Wales
SDLT does not apply. Scotland uses Land and Buildings Transaction Tax (LBTT); Wales uses Land Transaction Tax (LTT), each with its own rates and reliefs.
Do not treat the £541 million estimate as a discount available to everyday buyers; it concerns a specific high-value segment and a modeled tax comparison.
Calculate tax using the right national system and your expected completion date. Include any higher-rate or nonresident surcharge that applies.
Compare the purchase’s full cash cost—tax, deposit, mortgage, legal fees, and moving costs—rather than changing your offer solely because one month’s receipts moved.
Recheck official guidance if a Budget announces a policy change. Until rules change, today’s published rates are the basis for your estimate.
The headline is a warning about how sensitive luxury-property tax receipts can be to transaction volumes and policy expectations. For most homebuyers, the practical decision remains more specific: calculate the tax for your own property, buyer status, and UK nation, then decide whether the total cost fits your budget.