Home
» Today
»
Social Security COLA 2027: Latest Forecasts, Expected Increase, and What It Could Mean for Your Check
Social Security COLA 2027: Latest Forecasts, Expected Increase, and What It Could Mean for Your Check
The 2027 Social Security cost-of-living adjustment has not been announced yet. As of September 15, 2026, the most useful short-term forecasts cluster around roughly 3.4% to 3.6%, with The Senior Citizens League projecting 3.5% after the August inflation report and AARP estimating 3.6%. Those figures are forecasts, not an official benefit increase. The Social Security Administration will be able to calculate the actual COLA only after the Bureau of Labor Statistics releases September 2026 inflation data on October 14.
To make the numbers practical, this article follows a hypothetical example. Imagine Maria, a retired worker who currently receives $2,000 per month in gross Social Security benefits. Maria is not a real beneficiary and the figures below are not a prediction of any specific person's payment. Her example simply shows how different 2027 COLA outcomes would translate into dollars.
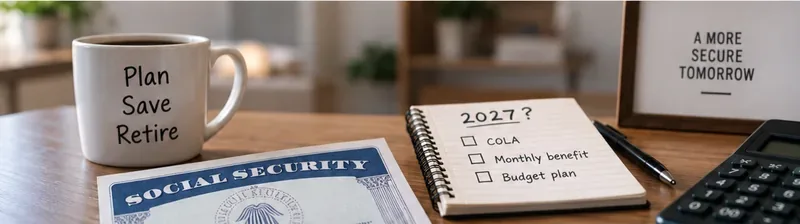
A retirement-planning setup for comparing possible 2027 Social Security COLA scenarios. The final COLA is not yet known.
What is the latest Social Security COLA forecast for 2027?
The latest widely cited estimates are higher than the 2.8% COLA applied for 2026, but they are still provisional. On September 11, 2026, The Senior Citizens League said its final pre-announcement model forecast was 3.5%, down slightly from 3.6% in August. AARP's September 11 analysis estimated 3.6%. A separate real-time inflation nowcast published September 14 calculated about 3.4% using the two actual third-quarter CPI-W readings available so far and an estimate for September.
There is also a longer-range official assumption from the Social Security trustees, but it should not be confused with a near-term forecast. The 2026 Trustees Report uses a 2.7% COLA assumption for calendar year 2026 under its intermediate economic assumptions. That figure was produced for long-term actuarial projections, not as a September 2026 nowcast of the COLA that beneficiaries will receive in January 2027.
How would a 3.4%, 3.5%, or 3.6% COLA change a monthly benefit?
For Maria's hypothetical $2,000 monthly benefit, the arithmetic is straightforward. A 3.4% adjustment would add $68 per month, 3.5% would add $70, and 3.6% would add $72. That would place her estimated gross monthly benefit at $2,068, $2,070, or $2,072 respectively before any deductions.
Current monthly benefit
At 3.4%
At 3.5%
At 3.6%
$1,500
$1,551.00
$1,552.50
$1,554.00
$2,000
$2,068.00
$2,070.00
$2,072.00
$2,500
$2,585.00
$2,587.50
$2,590.00
These are simple illustrations, not official benefit estimates. Social Security applies the COLA to a beneficiary's underlying benefit calculation and then determines the payable amount under its rounding rules. Your actual deposit can also differ from the gross benefit because of Medicare premiums, tax withholding, overpayment recovery, or other deductions.
How does Social Security actually calculate the 2027 COLA?
The law uses the Consumer Price Index for Urban Wage Earners and Clerical Workers, or CPI-W. The Social Security Administration compares the average CPI-W for July, August, and September 2026 with the average for July, August, and September 2025, the last third quarter used to determine a COLA. If the new average is higher, the percentage increase is rounded to the nearest one-tenth of one percent.
The 2025 third-quarter CPI-W average was 317.265. For 2026, July and August are already known. BLS reported a CPI-W index level of 328.481 for August 2026, and the index was 3.5% higher than a year earlier. The missing piece is September.
Why can the forecast still change after two of the three months are known?
Because September is one-third of the quarter used in the formula. If prices accelerate or cool sharply in September, the three-month average can move enough to change the final COLA by a tenth or more. That is why a forecast of 3.5% should not be treated as a promised raise.
For Maria, the difference between 3.4% and 3.6% is only $4 per month on a $2,000 benefit. That may look small in isolation, but the COLA becomes part of the benefit base used in future years, so even modest differences compound over time.
When will the 2027 COLA be official?
The Bureau of Labor Statistics has scheduled the September 2026 CPI release for October 14, 2026 at 8:30 a.m. Eastern Time. That release provides the last CPI-W number needed for the calculation. The Senior Citizens League and other analysts expect SSA to announce the official 2027 COLA that day.
The release date is listed on the BLS Consumer Price Index release calendar. Until then, any percentage attached to “Social Security COLA 2027” should be described as an estimate or projection.
When would the higher benefit show up?
Under current law, Social Security COLAs become effective with benefits payable for December and received by most beneficiaries in January. Supplemental Security Income generally receives the same percentage adjustment, with timing governed by SSI payment rules. SSA typically sends COLA notices showing an individual's new benefit amount after the official calculation is complete.
Maria should therefore avoid adding a forecasted $70 to her January budget as if it were guaranteed. A safer approach is to create a planning range. At 3.4% to 3.6%, she can provisionally model a gross benefit between $2,068 and $2,072, then replace that range with the official figure after the October announcement.
Is a bigger COLA the same as a real raise in purchasing power?
No. COLA is designed to help benefits keep pace with inflation, not to provide a bonus above inflation. A larger COLA usually means consumer prices have risen more quickly. In other words, a 3.5% adjustment can increase the dollar amount of a check while leaving a retiree's real purchasing power roughly unchanged if living costs also rose by a similar amount.
This distinction matters for household planning. Maria might see $70 more per month under a 3.5% scenario, but if groceries, housing, transportation, insurance, and other expenses have risen by a similar percentage, the extra money is largely compensating for higher prices rather than creating new discretionary income.
What does the current inflation data say?
BLS reported on September 11 that the broad CPI-U rose 3.4% over the 12 months ending in August 2026. The CPI-W, the measure actually used for Social Security COLAs, was up 3.5% over the same period. Those readings help explain why September forecasts moved into the mid-3% range.
However, the annual August change is not itself the COLA. SSA does not simply use one month's year-over-year inflation rate. It compares the average CPI-W across the full third quarter with the prior year's third-quarter average. That is an important distinction because headlines that quote “August inflation” can easily be mistaken for the final benefit adjustment.
How does the forecast compare with recent COLAs?
The official COLA was 2.5% for 2025 and 2.8% for 2026. A final 2027 adjustment in the 3.4% to 3.6% range would therefore be larger than either of the previous two adjustments, though still far below the unusually large 8.7% COLA that applied in 2023 after the inflation surge of 2022.
What could a 3.5% forecast mean for the average retired worker?
SSA's July 2026 statistical snapshot reported an average retired-worker benefit of about $2,085.98 per month. Applying 3.5% mechanically to that figure would produce an increase of roughly $73 per month, bringing the illustrative amount to about $2,159. This is useful for understanding scale, but it is not a forecast of the January 2027 national average because the beneficiary population and average benefit level can change before then.
The most useful step is not to chase every forecast change. Instead, treat the current 3.4%–3.6% range as a budgeting scenario until September CPI-W data arrive. Maria, for example, could keep her existing $2,000 benefit as the conservative baseline, note that current forecasts imply roughly $68 to $72 more per month, and wait for the official notice before committing that money to recurring expenses.
Use your actual current gross Social Security benefit, not a national average.
Run more than one scenario rather than budgeting from a single forecast.
Remember that Medicare and other deductions can affect the net deposit.
Check the October 14 CPI release and SSA announcement before treating any percentage as final.
Use the official SSA notice for your personalized 2027 amount.
Bottom line: what is the best estimate today?
As of September 15, 2026, the most defensible short answer is that the 2027 Social Security COLA appears likely to land somewhere around the mid-3% range, with prominent current forecasts at roughly 3.4% to 3.6%. The Senior Citizens League's latest forecast is 3.5%, while AARP estimates 3.6%. But the final percentage remains unknown because September CPI-W has not yet been released.
For a hypothetical $2,000 monthly benefit, that forecast range corresponds to roughly $68 to $72 more per month before deductions. The final answer should arrive after the September CPI report on October 14, 2026. Until then, the distinction between a forecast and an official COLA is the most important fact to keep in mind.