Home
» Today
»
Will Medicare Part B Premiums Reduce Your 2027 Social Security COLA?
Will Medicare Part B Premiums Reduce Your 2027 Social Security COLA?
For many retirees, the number that matters is not the Social Security cost-of-living adjustment by itself. It is the amount that actually reaches the bank account after Medicare premiums are deducted. That is why a higher Medicare Part B premium can make a Social Security COLA feel smaller even when the COLA itself has not been reduced.
As of September 15, 2026, two key 2027 numbers are still not final. The Social Security Administration (SSA) says the next COLA will be announced in October 2026, and the Centers for Medicare & Medicaid Services (CMS) has not yet announced the final 2027 standard Part B premium. The 2026 Social Security Trustees assumptions use a 2.7% COLA for the increase effective in December 2026 and generally paid beginning in January 2027, while the 2026 Medicare Trustees Report estimates a 2027 standard Part B premium of $209.50. Both figures should be treated as projections, not as your final personal amounts.
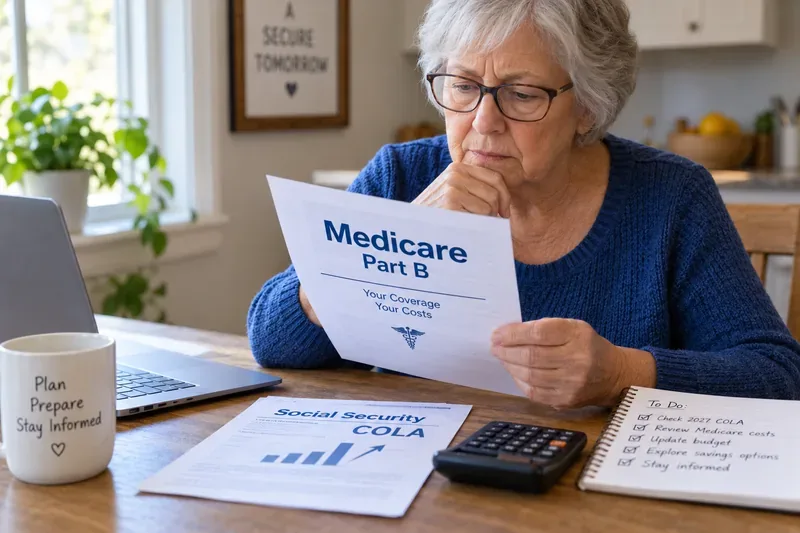
An older adult reviews Medicare Part B information alongside Social Security COLA materials, illustrating why retirees should compare the gross benefit increase with the premium deducted from the monthly payment.
First, understand the two numbers that affect your check
COLA means cost-of-living adjustment. Social Security uses it to raise benefits when the Consumer Price Index for Urban Wage Earners and Clerical Workers, or CPI-W, rises under the formula set by law. SSA compares the average CPI-W for July, August, and September with the relevant prior third-quarter average. SSA has stated that the next COLA will be announced in October 2026. You can follow the official calculation on the SSA COLA page.
Medicare Part B is the part of Medicare that generally covers physician services, outpatient care, certain home health services, durable medical equipment, and other medical services. Most people with Part B pay a monthly premium. For 2026, the standard premium is $202.90, according to the official CMS 2026 premium announcement.
For most people receiving Social Security, the Part B premium is automatically deducted from the monthly Social Security payment. Medicare explains this directly on its premium payment page. So even if your gross Social Security benefit goes up, a higher Part B premium can absorb part of that increase before you see the net deposit.
What is known about 2027—and what is not
Item
Status as of September 15, 2026
What it means
2027 Social Security COLA
Not yet final
SSA says the next COLA will be announced in October 2026.
Trustees assumption for the COLA payable in 2027
2.7% estimate
The 2026 Social Security Trustees assumptions use 2.7% for the COLA effective in December 2026. This is not the official COLA.
2026 standard Part B premium
$202.90, official
This is the current baseline for comparing a possible 2027 increase.
Estimated 2027 standard Part B premium
$209.50 estimate
The 2026 Medicare Trustees Report uses this estimate, but CMS can announce a different final amount.
The Medicare Trustees' $209.50 estimate would be $6.60 per month above the 2026 standard premium. The report itself notes that Part B financing rates have been set only through December 31, 2026, so the 2027 figure should not be presented as final. The source is the 2026 Medicare Trustees Report.
Could Part B actually reduce your 2027 COLA?
The best way to think about it is this: Medicare Part B does not change the COLA percentage that SSA applies to your Social Security benefit. Instead, a higher premium can reduce how much of the gross dollar increase remains in your net payment.
Consider a simple illustration using the Trustees' estimates, not final 2027 figures. Suppose your gross Social Security benefit before the new COLA is $2,000 per month. A 2.7% COLA would increase that gross benefit by about $54, to roughly $2,054. If the standard Part B premium rose from $202.90 to the Trustees' estimated $209.50, the premium increase would be $6.60. In this simplified example, you would keep about $47.40 of the $54 gross increase before considering any other deductions or adjustments.
That does not mean every beneficiary would see the same result. Your benefit amount, Part B premium category, income-related surcharges, enrollment status, premium payment method, and other deductions can all change the outcome.
Before you estimate your January payment, gather these four items
You do not need advanced financial tools. Start with information you already receive from Social Security and Medicare:
Your current gross Social Security benefit before Medicare deductions.
Your current Part B premium.
Whether your Part B premium is deducted from Social Security or billed separately.
Whether you pay an income-related monthly adjustment amount, commonly called IRMAA.
IRMAA is an extra Medicare premium amount charged to certain higher-income beneficiaries. For 2026, CMS says about 8% of people with Medicare Part B are affected by income-related premiums. SSA determines the higher premium using tax information provided by the IRS. Current rules and income thresholds are available on the SSA Medicare premium page.
Then estimate the effect in three simple steps
1. Estimate your gross COLA increase
Multiply your current gross monthly Social Security benefit by the COLA percentage you want to test. Until SSA announces the official percentage, use projections only for planning and label them clearly as estimates.
Subtract your current monthly Part B premium from the assumed 2027 premium. Using the Medicare Trustees estimate purely as an illustration: $209.50 − $202.90 = $6.60.
3. Subtract the premium increase from the gross COLA increase
Using the same simplified example: $54 − $6.60 = $47.40. That is the approximate portion of the gross increase left after only the change in the standard Part B premium. It is not a prediction of your exact deposit because other deductions may apply.
The hold-harmless rule can protect many beneficiaries
A major protection is the Medicare Part B hold-harmless provision. In general, this rule limits the increase in the Part B premium for qualifying beneficiaries so that the premium increase does not cause their net Social Security payment to fall because of the Part B increase.
SSA's policy guidance explains that qualifying beneficiaries are protected when the increase in the Part B premium would otherwise exceed the dollar increase in their Social Security benefit. You can read SSA's explanation in its hold-harmless overview and the more technical Program Operations Manual provision.
This is important because a small COLA does not automatically mean a protected beneficiary's net Social Security payment will drop solely due to a larger Part B premium increase. The premium may be limited for that person.
Who may not get hold-harmless protection?
The rule does not protect everyone. SSA and CMS identify important exceptions. Depending on your circumstances, protection may not apply if you are newly enrolling in Part B, if you pay an income-related premium such as IRMAA, if your Part B premium is not being deducted from qualifying Social Security benefits in the required months, or if a state Medicaid program pays your premium.
This distinction matters. A headline comparing the COLA percentage with the Part B premium increase can be misleading if it assumes every Medicare beneficiary is treated the same way.
Do not confuse a smaller net increase with a smaller COLA
One of the most common mistakes is saying that Medicare “cuts” the COLA. The COLA is applied to the Social Security benefit according to the statutory formula. Medicare deductions happen afterward when determining the net amount you receive.
For example, if your gross Social Security benefit rises by $50 but your Part B premium rises by $10, the COLA did not become $40. Your gross benefit still rose by $50; the higher Medicare premium used $10 of that increase.
This distinction also helps when comparing your benefit notice with the deposit that appears in your bank account. Look at the gross benefit, then the deductions, then the net payment.
Watch for IRMAA if your income recently changed
People who pay IRMAA should be especially careful about using a standard-premium estimate. Their total Part B premium can be substantially higher than the standard amount, and the hold-harmless protection generally does not apply to income-related Part B premiums.
If SSA used an older tax return showing higher income but your income later fell because of certain life-changing events, SSA allows you to request a new determination in qualifying situations. The agency points beneficiaries to Form SSA-44 for this process. Do not assume that retirement or another income change automatically updates IRMAA immediately; check the notice SSA sends you and follow the appeal or reconsideration instructions if appropriate.
What to check once the official numbers arrive
For a reliable personal estimate, wait until both the official Social Security COLA and the final 2027 Medicare Part B premium are available. Then compare:
Your 2026 gross Social Security monthly benefit.
The official 2027 COLA announced by SSA.
Your specific 2027 Part B premium, including any IRMAA if applicable.
Your Social Security COLA notice or online benefit information showing the new benefit amount.
SSA says the next COLA will be announced in October 2026. Medicare premium amounts are announced separately by CMS, so the two pieces of information may not appear on the same day. Your personal Social Security notice is more useful than a generic online calculator because it reflects your own benefit and Medicare deductions.
Common mistakes to avoid
Treating a projection as final. The 2.7% Social Security Trustees assumption and the $209.50 Medicare Trustees estimate are planning figures, not confirmed 2027 amounts.
Using the standard Part B premium when you pay IRMAA. Your actual deduction may be higher.
Assuming everyone receives hold-harmless protection. Eligibility depends on your specific enrollment and payment situation.
Comparing percentages instead of dollars. The hold-harmless calculation is about the dollar increase in your Social Security benefit compared with the dollar increase in your Part B premium.
Looking only at the bank deposit. Review the gross Social Security benefit and each deduction separately to understand what changed.
Bottom line: Part B may absorb part of the increase, but the final effect is not known yet
Yes, a higher Medicare Part B premium can reduce the amount of your 2027 Social Security COLA that you actually keep after deductions. But as of September 15, 2026, it is too early to state the exact impact because neither the official 2027 Social Security COLA nor the final 2027 standard Part B premium has been announced.
The current official baseline is a $202.90 standard Part B premium for 2026. The 2026 Medicare Trustees Report estimates $209.50 for 2027, while the 2026 Social Security Trustees assumptions use a 2.7% COLA for the increase payable beginning in 2027. Once SSA and CMS publish the final numbers, use your own gross benefit and premium category—not just national averages—to calculate what will happen to your net monthly payment.