Home
» Family
»
The Psychology of Spending: Why We Buy What We Buy—and How to Make Better Tradeoffs
The Psychology of Spending: Why We Buy What We Buy—and How to Make Better Tradeoffs
Why do smart, financially aware people still buy things they did not plan to buy? The simplest answer is that spending decisions are rarely just a calculation of price versus utility. A purchase can also promise convenience, relief, identity, status, belonging, novelty, or an immediate mood boost. The tradeoff is that every dollar used today gives up some flexibility tomorrow.
That tension matters in 2026 because consumers are making decisions in an environment where payments are increasingly frictionless and financing options are easy to place inside the checkout flow. The Federal Reserve's 2025 Survey of Household Economics and Decisionmaking, published in May 2026, found that prices were still the most common financial concern among U.S. adults. The same report said 16% of adults had used Buy Now, Pay Later (BNPL) in the prior year, and 11% of BNPL users reported that a payment had triggered an overdraft or non-sufficient-funds fee.
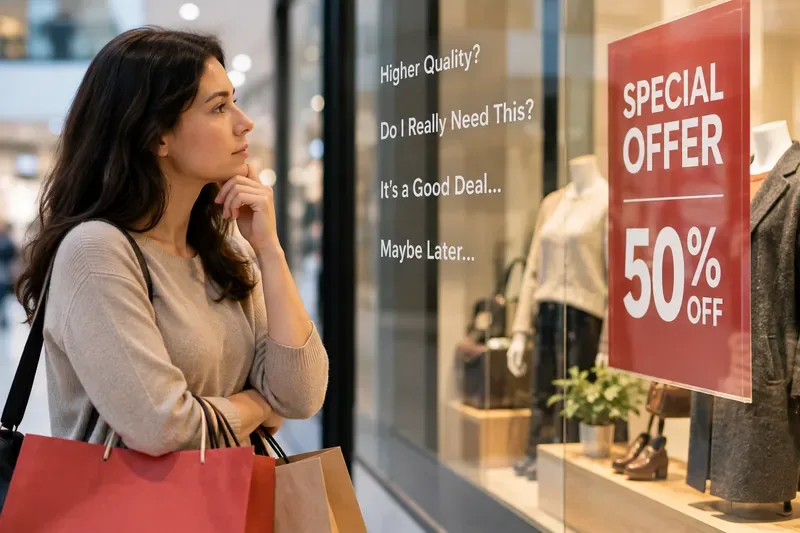
A shopper pauses in front of a sale display, illustrating the real-time tradeoff between an attractive deal, perceived need, and the option to wait.
Spending decisions are a contest between several kinds of value
A useful way to understand consumer psychology is to stop asking, “Why did I buy that?” as though there must be one cause. Most purchases combine several motives at once. A new phone may solve a practical problem, signal identity, reduce frustration, and create excitement. A restaurant meal may buy food, convenience, time with friends, and a break from cooking.
That does not make the spending irrational. The question is whether the benefits were worth the opportunity cost and whether the decision process gave enough weight to future consequences.
Immediate reward versus future flexibility
Behavioral economists use the idea of present bias to describe the tendency to give disproportionate weight to benefits and costs that occur now. David Laibson's work on hyperbolic discounting helped formalize why people can sincerely prefer saving in the abstract but still choose immediate consumption when the moment arrives. His research is available through Harvard's publication page on life-cycle consumption and hyperbolic discount functions.
This does not mean every impulse purchase is a mistake. Paying for a taxi instead of waiting for a bus may be a good trade if time is unusually valuable that day. The problem appears when immediate convenience repeatedly wins by default, even when the cumulative cost conflicts with a larger goal.
Best response: use a waiting period for purchases that are emotionally attractive but not urgent. A 24-hour pause is often enough for small discretionary items; expensive purchases may deserve a longer comparison window. This is most useful for shoppers who recognize the product first and justify the purchase second.
Mental accounting can help budgeting—and also distort it
People do not always treat every dollar as interchangeable. Richard Thaler's classic research on mental accounting and consumer choice describes how people mentally code gains, losses, transactions, and household budgets into different accounts.
This can be helpful. A separate “travel” account can make a long-term goal visible and protect it from everyday spending. Category budgets can also reduce decision fatigue by setting boundaries before temptation appears.
But mental accounts can also create loopholes. A tax refund, bonus, gift card, loyalty reward, or “money saved” during a sale may feel less valuable than ordinary income, even though it still represents purchasing power. Someone may spend $80 on an item because it is “$40 off,” even if they would never have chosen to spend $80 without the discount.
Best response: keep useful categories, but apply one universal rule to windfalls and discounts: judge the purchase by the dollars leaving your control, not by the size of the markdown or where the money came from.
The payment method changes the decision environment
Paying is not psychologically neutral. In a well-known neuroeconomic experiment, researchers found that product preference, price, and brain responses associated with anticipated gains and losses predicted subsequent purchase choices. The original study, “Neural Predictors of Purchases” in Neuron, supports the idea that buying involves competing reactions to getting something desirable and giving up money.
Research comparing payment methods has often found higher willingness to pay with cards than with cash, although the size and consistency of the effect vary by setting. A 2021 replication and extension found that the traditional “credit card effect” had weakened in some contexts and did not consistently carry over to mobile payments. That nuance matters: the replication study on credit cards and mobile payments is a reminder that payment psychology is not a universal law.
The practical tradeoff is straightforward. Credit cards and mobile wallets offer speed, fraud protections, recordkeeping, and sometimes rewards. Cash or a dedicated debit account creates more visible limits. Neither is automatically better.
Payment approach
Main advantage
Main tradeoff
Best fit
Cash
Highly visible spending and a hard physical limit
Less convenient; limited online use; no card rewards
People who overspend in specific discretionary categories
Dedicated debit account
Digital convenience with a defined spending pool
Requires account management and balance monitoring
People who want a digital version of an envelope system
Credit card paid in full
Convenience, purchase protections, rewards, consolidated records
Available credit can feel like available budget; interest is costly if a balance is carried
People with stable cash flow and reliable full-balance payment habits
BNPL
Predictable installment structure and short-term cash-flow flexibility
Multiple plans can obscure total obligations; missed payments can create fees or cash-flow stress
Occasional planned purchases when the full cost already fits the budget
“Affordable monthly payment” and “affordable purchase” are not the same thing
Splitting a price into four payments can make the immediate cost feel smaller without changing the total amount committed. That can be useful when timing is the only problem—for example, replacing a broken appliance a few days before payday when the household already has enough expected cash to cover every installment.
It becomes riskier when financing is used to make the purchase itself seem affordable. The Consumer Financial Protection Bureau's research on BNPL and other unsecured debt found that BNPL users often held other forms of credit as well. More recent Federal Reserve analysis published in August 2026 found that BNPL use was 31% among adults who could cover less than $100 of an emergency expense from savings, compared with 8% among those able to cover $2,000 or more. See the Fed's August 2026 Consumer & Community Context analysis.
Recommendation by need: if the goal is cash-flow smoothing, check the total outstanding installments across every provider before starting another plan. If the goal is making an unaffordable purchase feel affordable, the safer choice is usually to delay or reduce the purchase rather than optimize the payment schedule.
Social comparison changes what “normal” spending looks like
Humans do not choose in isolation. We learn what seems normal from friends, neighbors, coworkers, creators, and online communities. A useful piece of field evidence comes from the Dutch Postcode Lottery. Researchers studied neighborhoods where some households randomly received major lottery prizes and found spillover effects on certain visible forms of consumption, including cars and exterior home renovations among neighbors. The study is available from the National Bureau of Economic Research.
That does not mean seeing a neighbor's new car will automatically make someone buy one. It does show why comparison-heavy environments can shift the reference point for what feels ordinary or deserved.
Best response: compare a purchase with your own alternatives, not someone else's visible consumption. Ask: “What will I give up over the next month or year to pay for this?” That reframes the choice around opportunity cost instead of status.
Sales tactics can exploit the speed of decision-making
Countdown timers, low-stock messages, preselected add-ons, hard-to-cancel subscriptions, and visually dominant “sale” prices can reduce deliberation. Some urgency is legitimate: inventory really can be limited and promotions really do expire. The problem is false or manipulative urgency.
The Federal Trade Commission's “Bringing Dark Patterns to Light” report describes tactics such as baseless countdown timers, false limited-time claims, hidden information, and obstacles to cancellation. These practices matter psychologically because they shift the decision from “Is this worth buying?” to “Will I lose the chance if I do not act now?”
Best response: when urgency appears, evaluate the offer as if the timer were not there. Check the all-in price, cancellation terms, return policy, and competing options. A genuine deal should survive a basic comparison.
Which spending guardrail fits your actual problem?
The best system depends on the failure mode. Someone who forgets bills needs automation. Someone who impulse-buys after seeing discounts needs friction. Someone who carries credit card balances needs a different strategy from someone who pays the statement in full every month.
If your main problem is...
Try this first
Why it may help
Tradeoff
Impulse purchases
24- to 72-hour waiting list
Separates desire from immediate checkout
You may miss genuinely time-sensitive offers
Overspending in one category
Cash or a dedicated debit balance for that category
Makes the limit concrete
Adds friction and account management
Forgetting recurring charges
Monthly subscription audit and calendar reminder
Surfaces low-salience automatic spending
Requires a regular review habit
Credit card overspending
Real-time transaction alerts plus a weekly statement check
Makes otherwise abstract spending more visible
More notifications and attention
Irregular income
Base spending on a conservative income floor and keep variable money separate
Reduces lifestyle expansion after strong months
Can feel restrictive during good months
Social comparison
Use a personal “value per dollar” rule tied to your goals
Moves the reference point back to your own priorities
Requires knowing what those priorities are
Convenience is worth paying for—sometimes
A common mistake in spending advice is treating every extra cost as waste. Convenience has real value. Grocery delivery can save hours for a caregiver. A more expensive nonstop flight can preserve a workday. A premium tool can reduce repetitive work. The question is not whether convenience is “good” or “bad,” but whether its value is higher than the next-best use of the money.
A practical test is to price the alternative. If a $20 delivery fee saves 90 minutes and those 90 minutes are especially valuable that day, the trade can make sense. If the fee is paid five times a week only because ordering became habitual, the same convenience may no longer be worth the cumulative cost.
Rewards are useful only when they do not change the purchase
Cash back, points, coupons, and loyalty credits can lower effective cost. But they create value only if they do not cause a more expensive purchase, an unnecessary purchase, or interest charges that exceed the reward.
A simple rule is to calculate rewards after deciding to buy, not before. First decide whether the item is worth its full out-of-pocket cost. Then treat rewards as a secondary benefit. This prevents “earning” $10 from becoming the reason to spend $200.
A five-question self-check before checkout
No spending framework can eliminate emotion, nor should it. Enjoyment is a legitimate use of money. The goal is to make sure the emotional benefit is chosen rather than accidentally engineered by the checkout process.
Would I still want this tomorrow? If not, urgency or mood may be doing most of the work.
Would I buy it without the discount, points, or installment option? If not, the promotion may be defining the purchase.
What is the total cost, not the monthly payment? Include fees, financing costs, subscriptions, accessories, and expected maintenance.
What will this money displace? Name the alternative: savings, debt repayment, travel, another purchase, or simply more cash on hand.
Does the payment method help me control spending or hide it? Choose cash, debit, credit, or installments based on your behavior—not on what is fashionable or most frictionless.
The goal is not to spend less at all costs
Good spending is not defined by maximum frugality. It is spending that matches priorities, remains affordable after the excitement fades, and does not rely on hidden assumptions about future income or self-control.
If you value travel more than a newer car, spending heavily on travel can be rational. If you value time more than cooking every meal, paying for convenience may be rational. If rewards cards simplify your finances and you consistently pay in full, using them may be rational. Different people can make different choices from the same evidence because their constraints and goals differ.
The most useful psychological shift is to stop asking, “Is this a good deal?” and ask, “Is this a good trade for me?” A deal compares the price with another price. A trade compares the purchase with everything else the money could do.
This article is for general educational purposes and is not individualized financial advice.