Coffee Culture: How to Brew the Perfect Cup at Home

Fix bitter, sour, or weak coffee at home with a practical guide to beans, grind size, water, ratio, temperature, pour-over technique, and tasting.
The most important change in personal finance apps in 2026 is not a prettier spending chart. It is the move from passive dashboards toward software that can interpret your financial data, flag what deserves attention, and—in some cases—prepare changes for you to approve.
That shift is now verifiable. Copilot Money opened a public beta of its Money Assistant on April 16, 2026, describing proactive briefings, suggested recategorizations, refund matching, and budget-related actions that require user approval. By August 12, Copilot said the beta assistant could create, update, and delete categories, budgets, transactions, recurring transactions, and rules, while still letting the user approve or dismiss suggestions. Quicken also introduced an AI Chat experience in Quicken Simplifi in 2026 that can use a customer's Simplifi data to answer questions and help with actions, with review and approval before changes are made. These are meaningful advances, but they are still evolving features rather than autonomous financial advisers. See the official Copilot Money Assistant announcement, Copilot product updates, and Quicken AI Chat documentation.
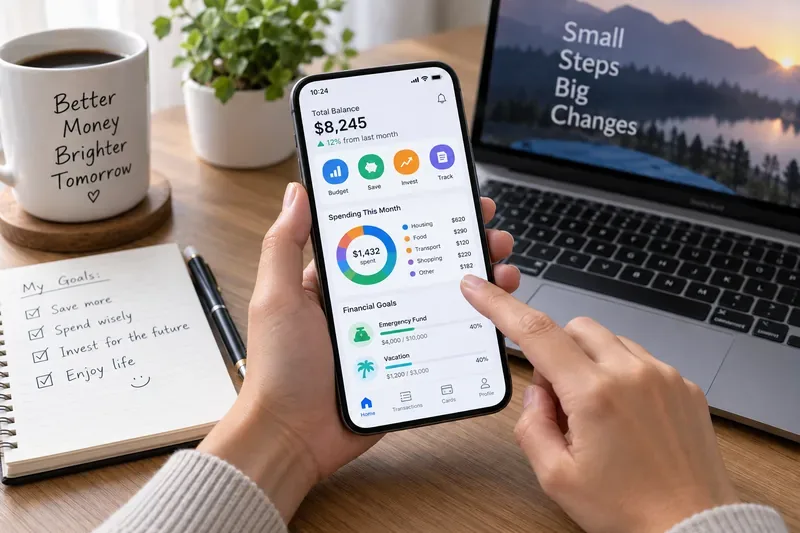
A finance app deserves that label only if it improves an outcome you can actually observe. The useful question is not whether an app has AI, colorful charts, or hundreds of bank integrations. It is whether the app helps you make better decisions with less friction.
For most people, there are five practical outcomes worth measuring:
If an app does not improve at least one of those outcomes after a reasonable trial period, switching tools may be more productive than adding more features or notifications.
| App | What stands out now | Best fit | Main limitation to watch |
|---|---|---|---|
| Copilot Money | AI categorization plus a Money Assistant beta that can surface issues and prepare account, budget, and transaction changes for approval | People who want a polished, automation-first view of U.S.-based finances | The assistant is still beta, and Copilot says the service supports U.S.-based accounts only |
| Quicken Simplifi | A cash-flow-oriented Spending Plan, recurring detection, and an AI Chat beta that can reason over Simplifi data | People who want a clear “left this month” view rather than a strict envelope system | AI availability and capabilities can change during beta |
| YNAB | Intentional, plan-first budgeting, goal tracking, household sharing, and more automated onboarding | People willing to actively decide what each dollar should do | It requires more behavioral participation than a passive tracker |
| Rocket Money | Subscription detection, cancellation support, budgeting, account alerts, net-worth tracking, and optional bill negotiation | People whose first priority is reducing recurring financial clutter | Some high-value features require Premium, and successful bill negotiation carries a fee |
| Monarch Money | Flexible or category budgeting, household collaboration, recurring tracking, investments, and net worth in one dashboard | Couples or households that want one shared financial operating view | Connected-account quality still depends on the institutions and data providers involved |
Copilot is one of the clearest examples of the 2026 move from “show me my money” to “help me understand what needs attention.” Its core app already tracks spending, budgets, subscriptions, investments, savings goals, cash flow, and net worth. Its Money Assistant beta adds a conversational and proactive layer over that data.
The important detail is the approval model. Copilot says the assistant can propose or carry out supported edits only with the user's approval. That is a more sensible design for money management than silently changing categories or budgets in the background. The company's official FAQ also makes several limits explicit: Copilot is not a bank, tax tool, credit-monitoring service, or financial adviser, and it currently supports U.S.-based accounts.
How to judge it: The assistant is useful if it reduces the number of manual searches, fixes, and budget adjustments you have to make while keeping the resulting data accurate. If you are correcting its suggestions as often as accepting them, the automation has not yet earned your trust.
Simplifi's Spending Plan remains one of its most practical differentiators. It organizes expected income, bills, subscriptions, planned spending, savings goals, and other spending, then updates the amount left for the month as transactions arrive. Quicken's May and June 2026 support documentation describes this as a real-time monthly planning system rather than a backward-looking expense report. See the official Spending Plan setup guide.
The newer layer is Quicken AI Chat. Quicken says it can answer natural-language questions using Simplifi data and can help with in-product actions after review and approval. Quicken also explicitly warns that AI responses can contain errors or incomplete information and should not be treated as investment, legal, or tax advice. That limitation is important, especially when a chatbot's confident tone can make a tentative answer sound definitive. The current disclosure is available in the Quicken AI disclosure.
How to judge it: Your “left this month” number should become more reliable as recurring items and transactions are matched. If the plan constantly needs manual correction because income, transfers, or bills are being interpreted incorrectly, the dashboard is not yet giving you decision-grade information.
YNAB remains different from apps that mainly observe spending after it happens. Its core method asks users to assign available money to priorities and targets. In 2026, YNAB has also been reducing setup friction. Its July 23 support update says that, during mobile onboarding for a first plan, YNAB can analyze 90 days of past spending and create targets automatically when there is enough data. That does not remove the planning philosophy; it gives new users a starting point they can edit. See YNAB's automatic target documentation.
YNAB also supports subscription sharing through YNAB Together, allowing a group of up to six people total to use one subscription with separate logins. Its feature page documents bank import, goals, loan planning, reports, and cross-device syncing. As checked in September 2026, YNAB lists its standard price at $109 per year or $14.99 per month before applicable tax on its official pricing page.
How to judge it: YNAB is working if your spending decisions increasingly happen before the purchase rather than only during an end-of-month review. If you want a mostly passive tracker and consistently resist assigning money to categories, another approach may fit better.
Rocket Money is compelling when the first problem to solve is not portfolio optimization but recurring financial leakage. Its current product materials emphasize subscription detection, spending tracking, budgeting, low-balance alerts, automated savings, net-worth tracking, and cancellation assistance. The free tier can show subscriptions; cancellation assistance and several advanced tools are Premium features.
Rocket Money also offers bill negotiation, but this is a case where reading the fee terms matters. Its July 27, 2026 help page says that if bill negotiation succeeds, the one-time fee is generally 35% to 60% of the first year's savings, with the percentage selected by the customer. See the official Rocket Money pricing and fee explanation.
How to judge it: Measure canceled subscriptions, avoided fees, or reduced recurring bills against what you pay for Premium or negotiation. A subscription-management app should produce visible financial or time savings; otherwise, a manual quarterly subscription review may be enough.
Monarch is particularly strong when personal finance is actually household finance. Its official feature pages describe shared views for separate and joint accounts, collaborative budgeting and goals, transaction review, recurring bills and subscriptions, net-worth tracking, investment tracking, and both Flex and Category budgeting.
That combination matters because couples often need different things at once: one person wants a high-level cash-flow view while the other wants category detail. Monarch's two budgeting approaches make that tradeoff less rigid. Its collaboration page and tracking features describe the current household and recurring-payment capabilities.
How to judge it: The benefit should show up in fewer “Which account paid for that?” conversations and a shared understanding of goals, cash flow, and upcoming bills. If connected accounts are frequently stale, however, the unified dashboard can create false confidence rather than clarity.
Personal finance software is only as useful as the data flowing into it. In July 2026, Quicken documented an upgraded OAuth API connection method in which users authenticate through a bank-hosted sign-in page instead of giving Quicken their bank password. YNAB has also added tools that can reset troubled bank connections and, when available, move a connection to a more suitable connector. Those changes are less flashy than an AI assistant, but they directly affect whether your dashboard stays accurate.
There is also a policy caveat. The U.S. Consumer Financial Protection Bureau's personal financial data rights framework under Section 1033 is intended to support consumer-authorized data access, but the CFPB says the rule's compliance dates were stayed by a federal court on October 29, 2025 while reconsideration continues. In other words, do not assume the U.S. open-banking rollout is legally or operationally settled. The current status is summarized on the CFPB's personal financial data rights page.
Do not grade an app by how many features you explored in the first week. Give it a full billing cycle, then look for evidence that the system is getting easier to trust and easier to maintain.
If those signals are improving, the tool is doing its job even if it is not the most feature-rich option. If they are not improving, more automation may simply create more cleanup.
Changing finance apps has a cost: reconnecting accounts, rebuilding categories, importing history, and learning a new workflow. That cost is worth paying when the current system repeatedly fails at the problem you hired it to solve.
Consider switching when your primary financial institutions remain unreliable after connection troubleshooting, when your budgeting method feels incompatible with how you make decisions, when important features are locked behind a price you cannot justify, or when an AI assistant creates more corrections than useful insight. Privacy can also be a deciding factor. Review what data an app can access, whether account connections are read-only, how authorization can be revoked, and whether you are comfortable with the provider's data policies.
No personal finance app can guarantee that you will save money, eliminate debt, or invest successfully. Categorization systems can be wrong. Linked balances can be delayed. A net-worth chart is only as complete as the accounts and assets included. Subscription detection can miss charges that are paid through an unlinked account. AI-generated explanations can also be incomplete or mistaken, which is why current products such as Copilot Money and Quicken AI retain approval steps and publish limits around advice.
The strongest use of these tools is therefore not to outsource judgment. It is to reduce the mechanical work required to see the situation clearly, so you can make the judgment yourself.
The personal finance apps changing the game in 2026 are moving in three directions at once: more proactive assistance, better automation of repetitive financial housekeeping, and stronger collaboration around shared money. Copilot Money and Quicken Simplifi show how AI is moving inside the financial dashboard. YNAB continues to push planning and behavior change while automating more of the setup. Rocket Money treats subscriptions and recurring bills as a core financial workflow. Monarch turns the household balance sheet into a collaborative workspace.
The best choice is not the app with the longest feature list. It is the one that gives you a more accurate picture, prompts useful action, fits the way you think about money, and remains trustworthy enough that you will still use it six months from now.
Feature availability, pricing, bank support, and beta functionality can change. Product details in this article were checked against official provider and U.S. government sources in September 2026. This article is for general educational purposes and is not individualized financial, investment, tax, or legal advice.
Fix bitter, sour, or weak coffee at home with a practical guide to beans, grind size, water, ratio, temperature, pour-over technique, and tasting.
Learn beginner-friendly winter houseplant care for light, watering, humidity, temperature, fertilizer, pests, and the mistakes that commonly damage plants.
Declutter your home without chasing perfection. Learn which spaces to tackle first, how clutter may affect stress and attention, and how to keep results manageable.
Discover which smart kitchen gadgets are genuinely useful, what to check before buying, how to set them up, and common beginner mistakes to avoid.
Functional beverages promise energy, hydration, gut support, protein, and more. Learn which benefits have evidence, what labels can hide, and how to choose wisely.
Learn practical zero-waste cooking habits that reduce food waste, stretch groceries, use leftovers safely, and turn edible scraps into useful meals.
Plan a cozy dinner party with the right guest count, make-ahead menu, warm atmosphere, food-safety basics, and a realistic hosting timeline.
Refresh your home for fall 2026 with budget-friendly decor trends, practical tradeoffs, and smart ways to add warmth, texture, and personality.
Compare practical meal-prep methods by time, flexibility, texture, cost, and food safety so you can build a weekday system that actually fits your life.
Make five reliable fall comfort-food recipes with clear doneness cues, troubleshooting tips, storage guidance, and realistic ways to adjust texture and flavor.







