Home
» Today
»
Why Meta Stock Is Trending: The AI Developments Investors Are Watching
Why Meta Stock Is Trending: The AI Developments Investors Are Watching
Updated September 21, 2026. Meta stock is drawing attention as the company moves its AI strategy from model announcements toward personal agents, subscription bundles, and everyday features across its apps. The newest product catalyst is Muse, an AI agent introduced in September; Meta One, announced a week later, adds paid plans with more AI usage. Investors are weighing that potential against a much larger infrastructure bill.
Those launches help explain why investors are watching Meta (NASDAQ: META), but they do not prove that AI is already a major source of revenue. Meta’s latest results still show an advertising-led business, while the company’s AI investment is expensive and its return will take time to measure. The latest company disclosures do not attribute any single day’s share-price movement to one product launch.
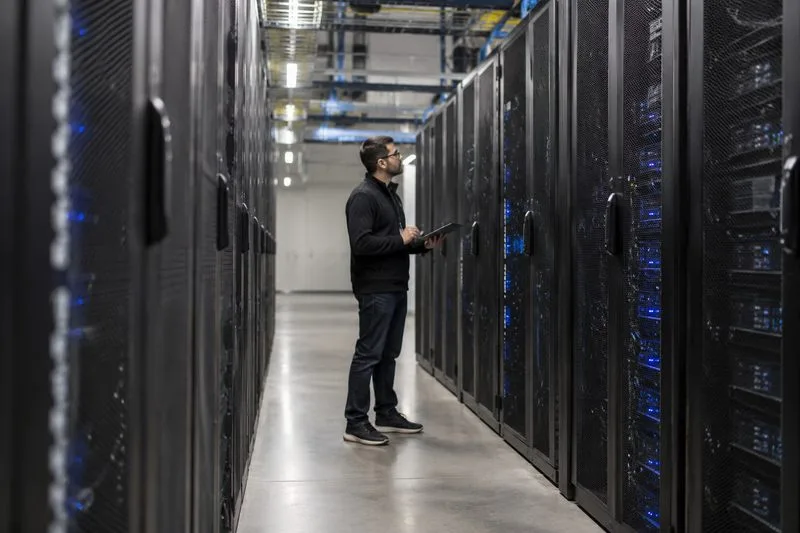
Server infrastructure is one part of the investment behind Meta’s AI products; investors are watching whether new services can generate returns that justify the cost.
Why is Meta stock trending now?
Two recent launches have made Meta’s AI plans more concrete. On September 8, Meta introduced Muse, a personal AI agent that can take actions such as sending an email or booking travel, and that may keep working after a user closes the app. On September 15, Meta announced Meta One, a subscription service with expanded AI usage, creator and business tools, and additional features across Facebook, Instagram, WhatsApp, and Meta AI.
These announcements give investors two questions to assess: Can Meta turn its enormous app audience into recurring paid customers, and can it make AI improve the advertising business that already pays most of the bills? The product releases create a story to follow, but the financial results will determine whether that story becomes a durable earnings driver.
What is Muse, and why are investors watching it?
Muse is designed to act on tasks rather than only answer prompts. Meta says it can help users plan goals, open a browser, fill in forms, and coordinate work across apps. It is powered by Muse Spark, the company’s latest model, and is rolling out in the United States through iOS, Android, and the web, with support through WhatsApp. Meta says users control how much access the agent receives and that it asks for approval before actions such as sending an email or making a purchase.
For investors, the strategic appeal is distribution. Meta can introduce an AI assistant through products people already use instead of asking each person to adopt a separate platform. An agent that helps complete practical tasks could encourage more use of Meta AI and create new reasons to return to WhatsApp or other Meta apps. But adoption, reliability, safety, and user trust are not guaranteed. A product announcement is not the same as evidence that people use an agent repeatedly or that the company can monetize it profitably.
Muse also depends on a broader model effort. Meta introduced Muse Spark in April as the first model from Meta Superintelligence Labs. The company has expanded Muse Spark-powered Meta AI features across its apps, and separately introduced Muse Image, its first image-generation model from the same lab. The scale of distribution could be valuable, but investors should look for reported usage and financial results rather than assume that more AI features automatically create more revenue.
Can Meta One turn AI interest into recurring revenue?
Meta One is a more direct monetization test. Meta describes individual plans with more usage of compute-intensive AI features, including image and video generation, as well as plans for creators and businesses. The company said the service launched with more than 50 features and reported 15 million subscriptions and trials to date. That figure combines subscriptions and trials; it should not be read as 15 million paying subscribers.
Meta says the basic experience across its apps and Meta AI will remain free. Paid plans are intended to sell higher limits, added creative tools, and professional features to people who want more. That could add subscription revenue and help fund costly AI services. Yet Meta has not disclosed in this announcement how much revenue the plans generate, how many trial users convert to paid plans, or how much subscribers spend on average. Those are key measurements to watch in future company reports.
Is AI already helping Meta’s core business?
The clearest current financial link is advertising. Meta’s filing says AI initiatives include content recommendations and advertising tools, and that its AI-powered discovery engine has already improved engagement and monetization of its products. That is an important distinction: AI can support the existing ad business even if consumers never pay separately for an AI assistant.
Meta’s second-quarter 2026 results offer measurable evidence about the underlying business, although they do not isolate the portion caused by AI. Revenue was $60.80 billion, up 28% year over year. Across the Family of Apps, ad impressions increased 14% and the average price per ad rose 12%. Meta reported 3.60 billion daily active people on average in June, up 3% year over year. Those numbers show a large and growing platform on which AI-driven recommendations and ad tools may build.
What are the main numbers investors should compare?
Signal
Latest company-reported figure
Why it matters
Second-quarter revenue
$60.80 billion, up 28% year over year
Shows the overall business is growing, but does not separate AI revenue.
Ad delivery and pricing
Impressions up 14%; average price per ad up 12%
Advertising remains the clearest evidence of monetization.
Costs and operating income
Costs and expenses up 55%; operating income down 8%
Spending and one-time items can pressure profit even as sales rise.
2026 capital spending outlook
$130 billion to $145 billion
Shows the scale of the infrastructure commitment investors expect to earn back.
The expense comparison deserves context. Meta reported $42.03 billion in second-quarter costs and expenses, including $2.40 billion in legal-proceeding charges and $1.18 billion in severance expenses tied to its May 2026 headcount reduction. Those items mean the 55% increase should not be treated as a pure measure of AI spending. Still, operating income fell 8% to $18.78 billion, underscoring that rapid revenue growth does not eliminate cost pressure.
Meta’s updated 2026 capital-expenditure range is $130 billion to $145 billion, including principal payments on finance leases, to support AI efforts and the core business. The company narrowed the previous $125 billion to $145 billion range by lifting its lower bound. Investors are watching whether new data centers, servers, and networking capacity translate into stronger ad performance, paid AI use, or both. Large spending may strengthen Meta’s future products, but it also raises the hurdle for returns and can affect cash flow and depreciation expense.
What could make the AI story disappoint?
First, users may try an agent without making it part of their routine. Agents also need to handle personal information and take actions reliably; privacy, security, and mistakes could limit adoption. Second, AI services consume computing capacity, so a popular feature can still have weak economics if operating costs grow faster than revenue. Third, Meta remains highly dependent on advertising. Changes in privacy rules, competition, advertiser budgets, or user engagement can affect results regardless of how capable its models become.
There is also execution risk. Meta is competing with other technology companies for AI talent, customer attention, and infrastructure. A new assistant or subscription tier could take time to reach enough users, and some users may prefer free alternatives. Meta’s filings discuss risks from regulation, competition, ad measurement, and large infrastructure investments. The company’s own outlook is therefore important alongside product announcements.
What should investors watch next?
Real adoption: Look for disclosed usage, retention, and geographic expansion for Muse, not just the number of launch features.
Paid conversion: Track paid subscribers separately from trials, along with renewals and revenue from Meta One plans.
Advertising returns: Compare ad impressions, average price per ad, and revenue growth to see whether AI improvements continue to support the core business.
Profit and cash flow: Watch operating expenses, operating income, capital spending, and depreciation as new AI capacity comes online.
Trust and regulation: Monitor how Meta handles privacy, agent permissions, user safety, and regulatory obligations.
Does the AI news make Meta stock a buy?
Not on its own. A new agent and subscription service can expand Meta’s opportunities, but investors still need to compare the share price with expected earnings, risks, and their own time horizon. The strongest evidence would be sustained paid adoption or measurable gains in advertising productivity without an unchecked rise in costs. Until Meta reports those outcomes, the AI developments are catalysts to monitor—not proof of a guaranteed stock return.