Home
» Today
»
How Inflation Is Shaping the 2027 Social Security COLA Forecast—and Why Seniors Are Still Struggling
How Inflation Is Shaping the 2027 Social Security COLA Forecast—and Why Seniors Are Still Struggling
Social Security beneficiaries are on track for a larger cost-of-living adjustment in 2027 than they received in 2026, but a bigger percentage does not automatically mean seniors will feel better off. As of September 15, 2026, two widely cited forecasts sit close together: The Senior Citizens League projects a 3.5% COLA, while AARP estimates 3.6%. The official number is not known yet because September inflation data—the final month used in the calculation—will not be released until October 14.
That distinction matters. A 3.5% or 3.6% increase would raise monthly Social Security checks, but the increase is designed to compensate for inflation that has already occurred. It is not a bonus, and it does not guarantee that every retiree's personal expenses will rise at the same pace as the index used by Social Security.
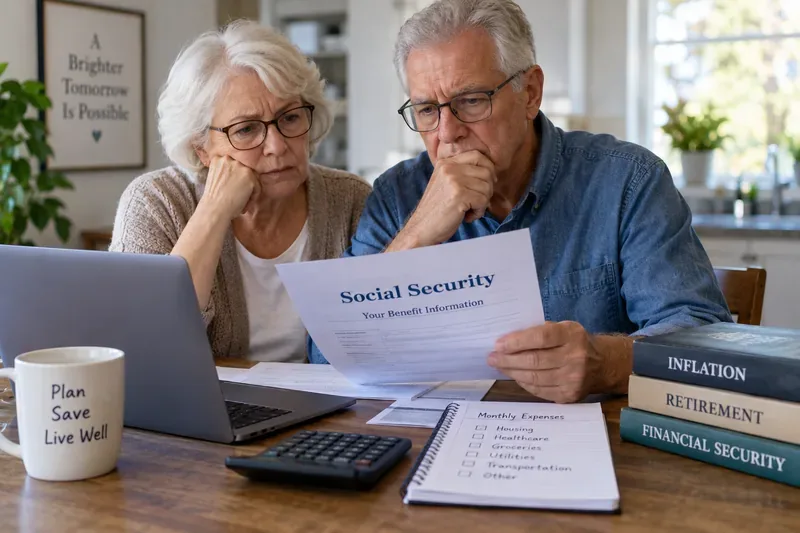
An older couple reviews a Social Security statement and household expenses, illustrating why the headline COLA percentage matters less than how the increase compares with actual housing, health care, food, and utility costs.
What is actually known about the 2027 COLA right now?
The verified part is the formula. Social Security uses the Consumer Price Index for Urban Wage Earners and Clerical Workers, or CPI-W. The Social Security Administration compares the average CPI-W for July, August, and September 2026 with the average for those same three months in 2025, then rounds the increase to the nearest tenth of a percentage point. The 2025 third-quarter average was 317.265. The methodology is explained on the Social Security Administration's COLA calculation page.
Two of the three 2026 months are now available. The Bureau of Labor Statistics reported a CPI-W reading of 327.104 for July and 328.481 for August. August CPI-W was 3.5% higher than a year earlier. BLS also reported that the broader CPI-U rose 3.4% over the year through August, while gasoline prices rose sharply during the month. Those figures can be checked in the BLS August 2026 CPI release.
The uncertain part is September. BLS has scheduled the September CPI release for October 14, 2026. Until that number is available, any 2027 COLA percentage is a forecast rather than an official benefit increase.
Why the forecast is clustering around 3.5% to 3.6%
The Senior Citizens League lowered its September forecast to 3.5%, down from 3.6% a month earlier. Its current estimate is published in the organization's September 11, 2026 COLA forecast. AARP's September analysis puts the number at 3.6%.
These figures are illustrations, not individual benefit estimates. Social Security applies the COLA to each person's underlying benefit calculation, so the exact dollar increase varies.
A higher COLA can be good news and bad news at the same time
The main tradeoff is easy to miss: a higher COLA usually means inflation was higher. If the final 2027 adjustment lands near 3.5% or 3.6%, beneficiaries will get more dollars, but those dollars are intended to offset higher prices rather than create a comparable gain in living standards.
This is why comparing COLA percentages as if a bigger one were automatically “better” can be misleading. The 8.7% COLA for 2023 was much larger than recent increases, but it followed unusually high inflation. By comparison, the 2026 COLA was 2.8%, according to the SSA's 2026 COLA fact sheet.
For someone choosing how to budget, the practical question is not “Is 3.6% better than 3.5%?” It is “How much will my recurring expenses rise compared with my net Social Security payment?” A tenth of a percentage point on a roughly $2,086 benefit is only about $2 per month.
Why seniors can still feel squeezed even when the COLA rises
1. The COLA uses CPI-W, not a retiree-specific official index
CPI-W reflects spending patterns of urban wage earners and clerical workers. BLS says that this population is a subset of the broader CPI-U population and represents about 30% of the U.S. population. It is the measure required by law for Social Security COLAs.
BLS also publishes a research index for Americans age 62 and older, called the R-CPI-E. It is not used to set Social Security benefits, and BLS explicitly warns that the research index has limitations. Still, its existence highlights a real budgeting issue: older households can allocate their spending differently, especially to housing and medical care. Readers can review BLS's description and caveats on the R-CPI-E research page.
Best response if your budget is health-care heavy: track your own annual change in premiums, prescriptions, copays, dental care, and out-of-pocket services rather than assuming the COLA percentage measures your personal inflation rate.
2. The adjustment arrives after the price increases used to calculate it
The 2027 COLA is based on price levels in the third quarter of 2026, but the higher Social Security payments do not begin until benefits payable for December 2026, which beneficiaries receive in January 2027. In other words, retirees must absorb current price increases before the corresponding annual adjustment appears in their checks.
Best response for retirees with little cash cushion: avoid treating a projected COLA as spendable income before the official October announcement and before you know your January net payment.
3. Medicare can absorb part of the gross increase
Many Medicare beneficiaries have their Part B premium deducted directly from Social Security. The standard Part B premium is $202.90 per month in 2026, according to Medicare.gov.
The 2026 Medicare Trustees Report estimates a standard 2027 Part B premium of $209.50, which would be $6.60 higher per month, but that is an estimate rather than the final 2027 premium. The projection appears in the official 2026 Medicare Trustees Report. Because the final premium can differ, it is safer to budget using a range rather than subtracting $6.60 as if it were guaranteed.
Best response if you are enrolled in Medicare: compare your final 2027 Social Security amount with your final Part B, Part D, Medicare Advantage, or Medigap costs. Gross COLA and net spendable income are not the same number.
4. Essential categories can move very differently from headline inflation
August's CPI report shows why household experience can diverge from the overall 3.4% CPI-U inflation rate. Energy prices were 16.3% higher than a year earlier, gasoline was up 27.4%, shelter was up 3.0%, and food was up 2.7%. Medical care was up 1.6%. Those are national averages, and they do not mean every retiree experienced those exact changes, but they show why one all-items inflation number cannot describe every household.
Best response if transportation or utilities dominate your budget: build your 2027 spending plan from your actual bills, not from the COLA percentage alone.
Which planning approach makes the most sense?
Your situation
More useful approach
Main tradeoff
Social Security is only part of your income
Model the COLA together with pensions, withdrawals, wages, and taxes
A slightly higher COLA may matter less than investment income or tax changes
You depend heavily on Social Security
Use a conservative 2027 budget until the October figure and Medicare costs are known
More caution now, but less risk of committing future income too early
Health costs are unusually high
Focus on net benefits after premiums and expected out-of-pocket costs
The headline COLA may overstate your usable increase
Housing is your largest expense
Compare rent, property tax, insurance, utilities, and maintenance increases separately
Your personal inflation rate may differ substantially from CPI-W
You have discretionary savings
Consider directing part of the increase to an emergency or medical reserve
Less immediate spending, more protection against later price shocks
What the latest forecasts do—and do not—tell us
As of September 15, the available evidence supports saying that the 2027 Social Security COLA is likely to be higher than the 2.8% adjustment for 2026, with prominent forecasts around 3.5% to 3.6%. It does not support saying that either forecast is final.
It also does not support the idea that a higher COLA automatically solves affordability problems for seniors. The adjustment protects against broad measured inflation, but it cannot ensure that every beneficiary keeps pace with a personal mix of rent, property taxes, insurance, food, utilities, transportation, and health care. It also arrives annually, while prices can change throughout the year.
The most useful way to prepare is therefore to separate three numbers: the official COLA percentage, your gross Social Security increase, and the net amount left after Medicare and other recurring costs. For seniors living on a tight margin, that third number is the one that determines whether 2027 actually feels easier.
What to watch next
October 14, 2026: BLS is scheduled to release September CPI data, completing the three-month period needed for the COLA calculation.
Official Social Security announcement: SSA can calculate the 2027 COLA once the September CPI-W is available.
2027 Medicare costs: watch for final Part B premiums and your plan-specific Part D or Medicare Advantage costs before estimating your January net benefit.
Your personalized notice: use your actual Social Security notice rather than applying a forecast percentage to a bank deposit, because individual benefit calculations and deductions differ.
Until those pieces are final, a range is more useful than a single prediction. Planning around roughly 3.4% to 3.6% can help with scenarios, but only the official October calculation should be treated as the 2027 Social Security COLA.